21??
Apr 20th
Oil price also wrong
TCS Ltd. (NSE: TCS) — Q1 FY27 Earnings Analysis | Current Share Price: ₹2,069
Reporting Period: Q1 FY27 (Quarter ended June 30, 2026) | Analysis Date: July 12, 2026
## 1. Headline Financials & Performance Matrix
TCS reported a steady double-digit jump in its year-on-year (YoY) revenue, though sequential profitability felt expected seasonal pressures.
Revenue from Operations: Reached ₹72,275 crore, growing a powerful 13.93% YoY and 2.23% sequentially (QoQ) over Q4 FY26. This comfortably outperformed consensus estimates of ₹71,847 crore.
Net Profit (PAT): Reported at ₹13,349 crore, an increase of 4.62% YoY. Sequentially, PAT dipped 2.69% QoQ from ₹13,718 crore due to seasonal wage hikes and a $70 million (~₹585 crore) legacy trade-secret lawsuit settlement.
Note: Excluding exceptional items like the legal settlement, normalized net profit rose 8.5% YoY to ₹13,849 crore.
Interim Dividend: The board declared a first interim dividend of ₹12 per share (Record Date: July 15, 2026; Payout Date: July 31, 2026).
## 2. Margins & Operational Metrics
Operating Margin (EBIT): Came in at 24.0% (down 130 basis points sequentially from 25.3% in Q4 FY26). The contraction was largely engineered by the rollout of global annual salary increments.
Net Margin: Maintained an industry-leading 19.2% (excluding exceptional items).
Cash Conversion: Handled cash with peak efficiency; net cash generated from operations stood at ₹12,412 crore, translating into 93% of its net income.
## 3. Strong Deal Pipeline & The $2.6 Billion AI Engine
Despite global macroeconomic headwinds, client commitment to long-term digital transformations remains highly intact:
Total Contract Value (TCV): Secured robust new order wins worth $9.5 billion during the quarter.
Mega Deal Catalyst: Marquee wins included a massive $800 million global business transformation deal with engineering giant SKF, alongside deep multi-million-dollar expansions with ServiceNow, Anthropic, and Mistral.
AI Scale-up: The annualized AI revenue run-rate reached an incredible $2.6 billion, reflecting a 13.6% sequential jump. TCS is successfully moving beyond AI pilots and monetizing production-level enterprise generative AI.
## 4. Segment & Regional Growth Dynamics (Constant Currency)
Growth was unevenly distributed across verticals and regions, reflecting specific pockets of global tech optimization:
Vertical Performance
BFSI (Largest Contributor): Stabilized cleanly, expanding 13.15% YoY and 1.6% QoQ.
Life Sciences & Healthcare: Emerged as a major growth driver, jumping 15.68% YoY.
Communications, Media & Tech: Expanded 12.48% YoY.
Consumer Business: Experienced softness, shrinking 4% QoQ as retail clients deferred non-essential discretionary tech budgets.
Regional Performance
India Market: Displayed hyper-growth, sky-rocketing 22.9% YoY.
North America (Primary Market): Grew a modest 2% YoY but contracted slightly by 0.4% QoQ, proving that US clients remain relatively cautious with experimental tech spend.
Continental Europe: Grew at a healthy clip of 4.3% YoY.
## 5. Human Capital & Attrition Stability
Unlike recent quarters where the IT industry saw shrinking headcounts, TCS returned to aggressive talent acquisition:
Net Employee Addition: Added 9,279 net professionals in Q1, bringing the total global workforce to 593,798.
Attrition Rate: The Last Twelve Month (LTM) IT services attrition rate stabilized comfortably at 13.6%, providing relief from the talent wars of prior years and paving the way for lower sub-contracting costs down the line.
## Management Commentary & Forward Outlook
CEO K. Krithivasan indicated that despite regional friction—such as temporary delays tied to the West Asia conflict—enterprise tech backlogs are immense. Management strongly expects global demand to pick up sequentially in Q2 FY27, as clients accelerate investments to modernize legacy platforms, sovereign cloud architectures, and cybersecurity.
## Verdict
TCS has set a steady, confident tone for the IT sector for FY27. By crushing top-line projections, locking down a $9.5 billion TCV pipeline, and scaling its AI footprint to $2.6 billion, the fundamentals are firing on all cylinders. The minor margin dip from wage revisions and a legal settlement is entirely cyclical, making this a highly resilient scorecard for market heavyweights.
Disclaimer:
This analysis is strictly for educational and informational purposes only and does not constitute financial or investment advice. IT sector investments carry structural market risks influenced by global macro factors and currency fluctuations. Please consult a SEBI-registered financial advisor before executing any market allocations.
1 Like
 South Korean Markets Up Over 100% in a Year Amid Extreme Volatility
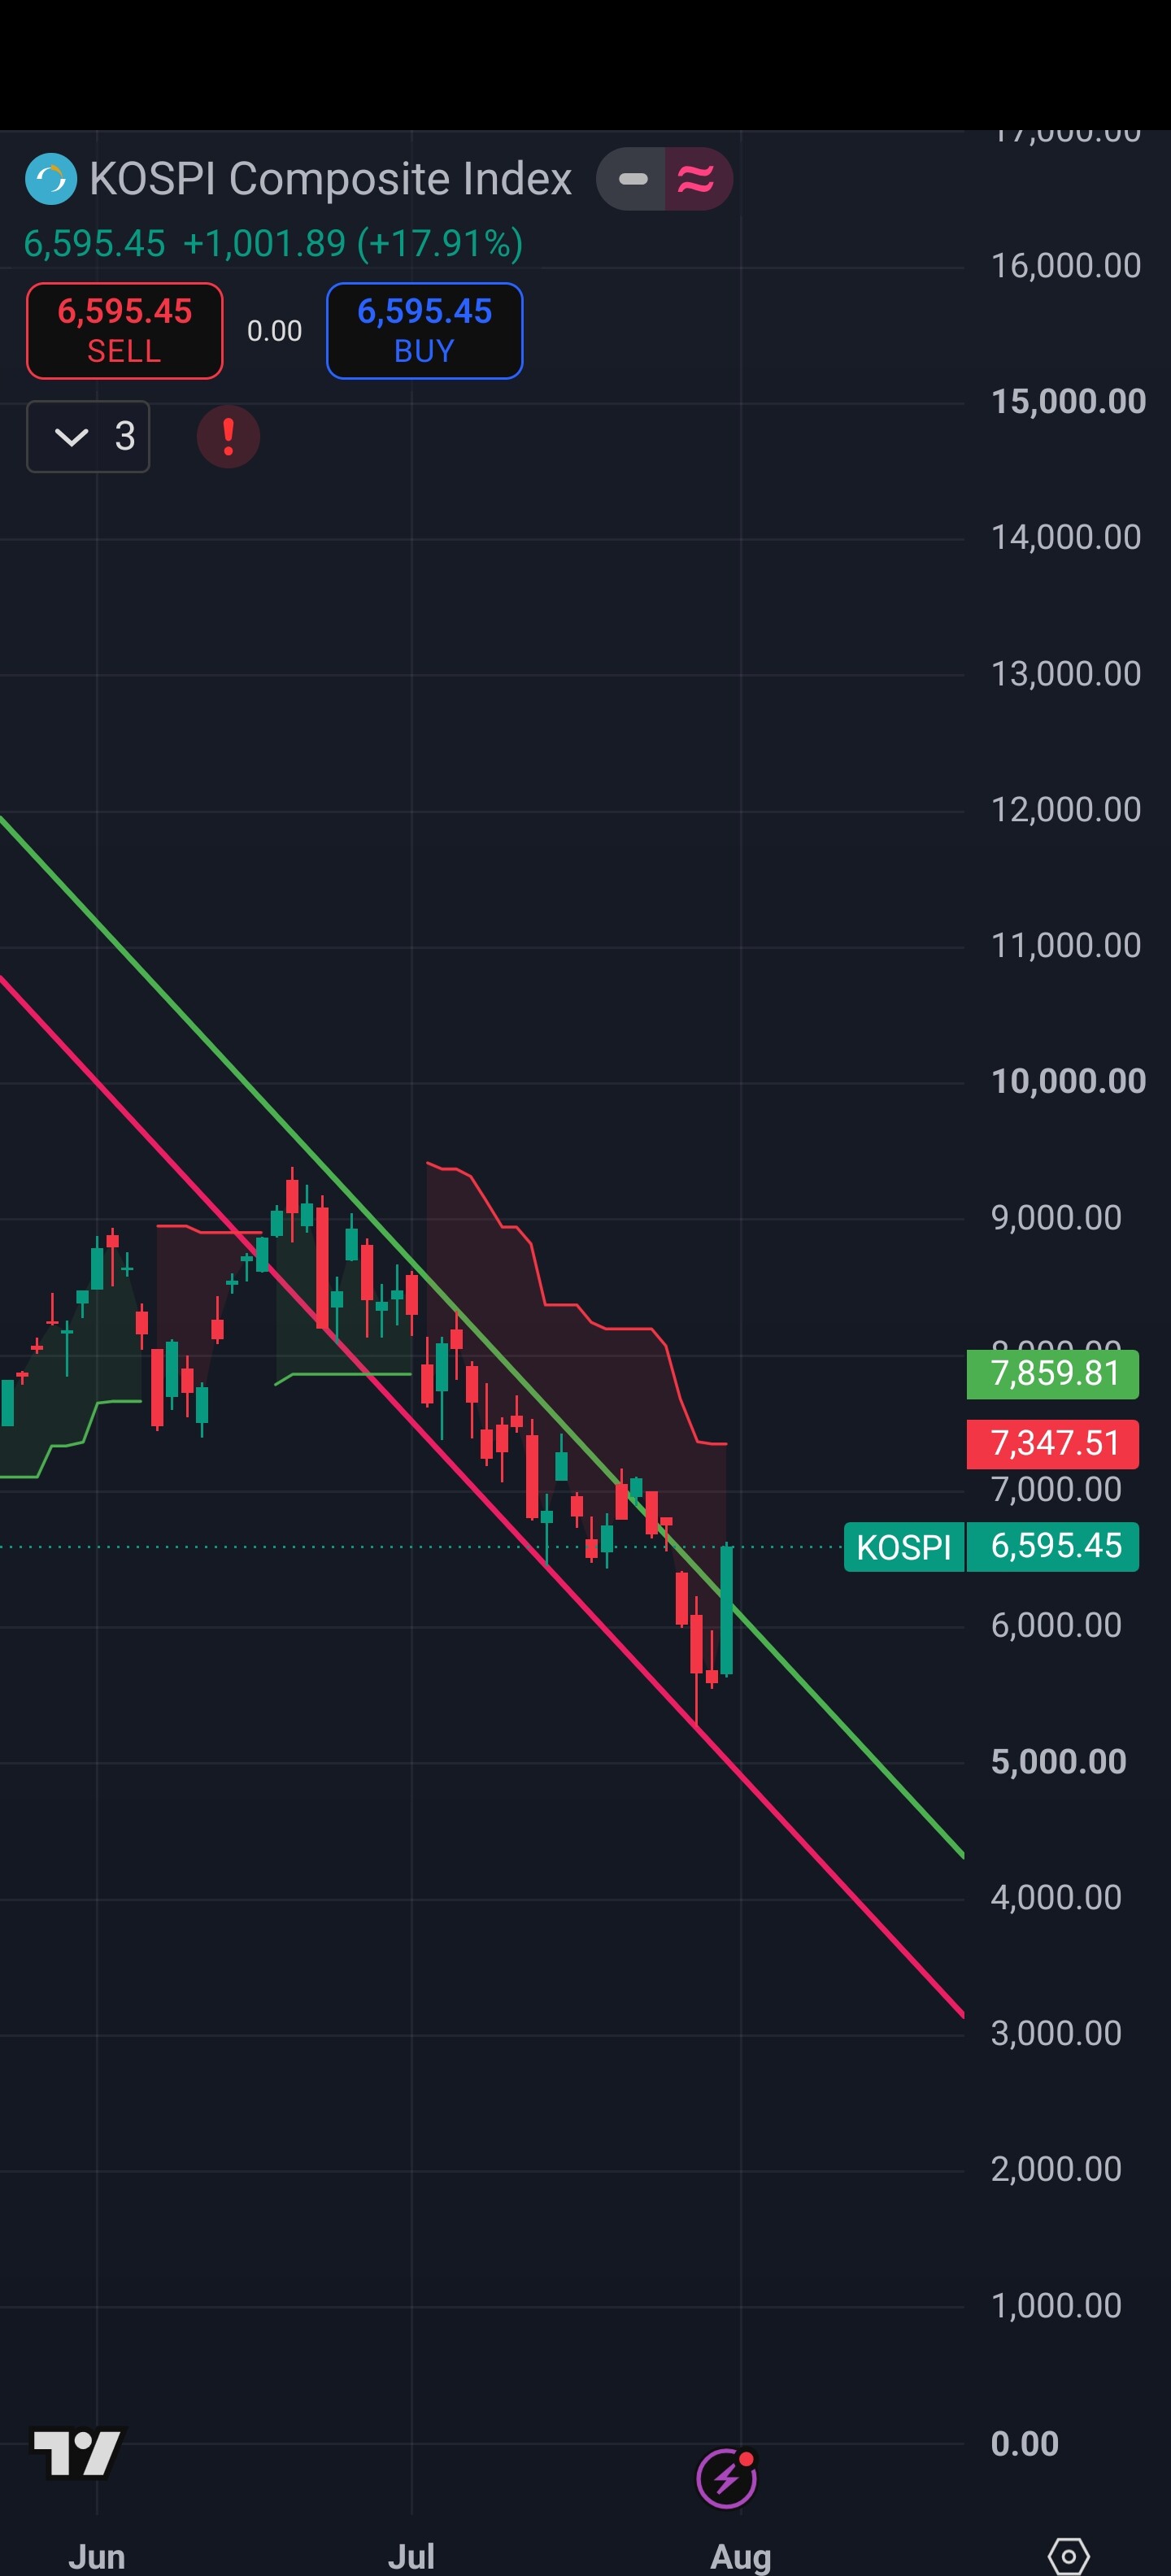
 South Korea’s benchmark KOSPI Index has delivered one of the world’s strongest equity rallies, rising over 100% in the last 12 months, while experiencing unprecedented volatility. On July 31, 2026, the KOSPI closed at 6,595.45, surging 17.91% (+1,001.89 points)—the largest single-day percentage and point gain in the index’s history.
 One-Year Journey
 July 2025: ~3,100–3,250 (AI-led accumulation phase)
 January 2026: Crossed 5,000 for the first time.
 June 18, 2026: Reached an all-time high of 9,385.59, nearly 200% above July 2025 levels.
 Late July 2026: Corrected to around 5,593, falling nearly 40% from its peak.
 July 31, 2026: Rebounded to 6,595.45 with a historic 17.91% single-day gain.
What Drove the Rally?
The rally was led by AI semiconductor giants Samsung Electronics and SK Hynix, supported by robust AI infrastructure spending, strong foreign institutional inflows, and improving investor sentiment. The sharp surge also triggered a buy-side sidecar trading halt shortly after the market opened.
 Why So Much Volatility?
July became one of the most volatile months in KOSPI’s history due to:
- Leveraged ETF unwinding and margin calls.
 Heavy concentration of the index in semiconductor stocks.
 Foreign institutional profit booking after the sharp rally.
 Emerging Global Market Trend: Indian IT vs. AI Hardware
Over the past few weeks, an interesting relationship has emerged between Indian IT stocks and global AI hardware stocks.
 When global AI hardware stocks decline, investors have increasingly rotated into Indian IT companies such as TCS, Infosys, HCLTech, and Wipro, viewing them as relatively defensive, asset-light beneficiaries of enterprise AI spending.
 When global AI hardware stocks rally, capital rotates back into semiconductor leaders such as Samsung Electronics, SK Hynix, NVIDIA, and other AI chipmakers, resulting in relative weakness in Indian IT stocks.
 Today’s trading session reinforced this trend. As South Korean semiconductor stocks staged a historic rally, Indian IT stocks traded lower, reflecting a shift in investor preference back toward AI infrastructure and chip manufacturers.
While this inverse relationship has become increasingly visible in recent weeks, it remains a short-term market trend and could evolve as earnings, valuations, and global macroeconomic conditions change.
 Conclusion
The South Korean stock market has experienced one of the most remarkable boom-and-bust cycles in recent history. Although the KOSPI has more than doubled over the past year, the sharp correction and subsequent record rebound highlight the risks of concentrated leadership, leverage, and rapid sector rotation. The recent divergence between global AI hardware stocks and Indian IT stocks also underscores how quickly global capital is rotating across different segments of the AI ecosystem.
1 Like
Global Bond Yields Surge — Why It Matters for Global & Indian Stocks
Global bond markets are experiencing a sharp sell-off, pushing government bond yields to multi-year or multi-decade highs. The move is becoming an important risk factor for equity markets, including India.
What is happening in the bond market?
 US 10-year Treasury yield: around 4.8%, with the yield touching its highest level since November 2023.
US 30-year yield: above 5.2%.
 Japan 10-year yield: reached 3%, the highest since 1996.
 Germany 10-year yield: around 3.3%, near a 15-year high.
 UK 10-year gilt yield: around 5.25%, while the 30-year yield has moved close to 5.9%.
This is not simply a US Treasury story—the simultaneous rise in yields across major economies suggests a broader repricing of global borrowing costs.
 Why are yields rising?
-
Higher inflation expectations

The renewed Middle East conflict has pushed Brent crude towards the mid-$90s. Higher energy prices can feed into inflation, making markets worry that central banks may keep rates higher for longer or even tighten policy. -
Government debt & fiscal deficits
Large government borrowing requirements are increasing bond supply. Investors are demanding higher yields to absorb that supply and compensate for fiscal risks. US federal debt has surpassed $40 trillion. -
Central-bank rate expectations

With inflation risks increasing, markets have sharply raised expectations for further US rate increases. -
Corporate borrowing — especially AI investment

Large technology companies are also issuing substantial amounts of debt to finance AI infrastructure, adding to the supply of bonds competing for investor capital.
Why rising yields are negative for stocks
There are three major transmission channels:
 Higher discount rate → lower valuations
Stock valuation models discount future earnings using interest rates.
Bond yield ↑ → discount rate ↑ → present value of future earnings ↓
This is particularly important for high-growth and technology stocks, where a larger portion of their valuation depends on future earnings.
 Bonds become more attractive
When government bonds offer higher yields, investors may become less willing to take equity risk.
Higher risk-free return → higher hurdle rate for stocks → pressure on equity valuations.
This can be particularly significant for expensive markets.
 Corporate borrowing becomes expensive
Higher bond yields increase financing costs for companies.
That can affect:
Capital expenditure
Expansion plans
M&A activity
Refinancing
Profit margins
Ultimately, weaker investment and slower economic activity can hurt corporate earnings.
 Impact on Indian Stock Market
India is particularly sensitive to global yields because of its position as a major emerging market.
1. FPI/FII flows could come under pressure
When US Treasury yields rise significantly, US assets become more attractive relative to emerging-market assets.
Potential flow:
US yields ↑ → dollar assets more attractive → FPI money may leave emerging markets → Indian equities face selling pressure
This does not mean foreign investors will automatically sell India, but the relative attractiveness of Indian equities can decline.
 2. Pressure on the Indian rupee
Foreign portfolio outflows can put pressure on the rupee.
A weaker rupee can increase the cost of imported commodities, particularly crude oil, creating another inflationary pressure.
3. Indian bond yields can rise
The global bond sell-off is already transmitting into Indian government bonds. India’s 10-year government bond yield has been moving towards the 7% psychological level as US Treasury yields rise and oil prices increase.
Higher domestic yields can subsequently increase borrowing costs throughout the economy.
4. RBI policy becomes more complicated
India faces a difficult combination:
Higher crude oil + weaker rupee + global yields ↑
This can make monetary easing more difficult and could keep domestic borrowing costs elevated.
Which Indian sectors could be affected?
 More vulnerable
IT & Technology 
Global growth concerns + higher discount rates can pressure valuations.
Real Estate 
Higher interest rates increase financing costs and can affect housing demand.
Consumer Discretionary 
Higher borrowing costs can reduce consumer spending.
Capital-intensive companies 
Companies with high debt or large refinancing requirements may face higher interest expenses.
High-valuation growth stocks
These tend to be particularly sensitive to changes in long-term bond yields.
 Potential relative beneficiaries
Banks & Financials
The impact is mixed. Higher yields can support lending yields, but rising funding costs and weaker credit demand can offset the benefit.
Insurance companies
Higher bond yields can potentially improve reinvestment returns on fixed-income portfolios.
Energy companies 
Higher crude prices can benefit upstream producers, although the impact varies significantly by company and government policy.
The bigger risk: Yield + Oil combination
For India, the combination is more important than bond yields alone.
 Global yields ↑
Crude oil ↑
Rupee ↓
FPI outflows
=
Higher pressure on Indian equities
This is why the current global environment deserves close attention.
Recent market action already shows the relationship: US equities came under pressure as Treasury yields and oil prices rose, while India’s 10-year yield moved higher alongside the global bond sell-off.
 What should investors watch next?
Key global indicators:
US 10Y Treasury — 4.8%–5% zone
Japan 10Y — 3%+
Germany 10Y — 3.3%+
UK 10Y — 5%+
Brent crude — $90–$95+
Dollar index & USD/INR
FPI flows into Indian equities and bonds
RBI & Fed policy expectations
A sustained move towards or above 5% in the US 10-year Treasury yield would be an important psychological signal for global equity investors.
Bottom Line
Rising global bond yields are becoming one of the biggest macro risks for equity markets.
For India, the concern is not simply “US yields are rising.”
The bigger issue is:
US yields ↑ → global liquidity tightens → FPI flows weaken → rupee pressure → Indian bond yields ↑ → valuation pressure on equities
If crude oil remains elevated at the same time, the pressure could become stronger.
Therefore, investors should closely monitor US 10-year yields, Brent crude, USD/INR and FPI flows alongside Nifty.
Disclaimer: This report is for educational and informational purposes only. It is not investment advice, a recommendation, or a guarantee of future market performance. Bond yields, currencies, crude oil and equity markets can change rapidly. Investors should conduct their own research and consult a qualified financial adviser before making investment decisions.
1 Like