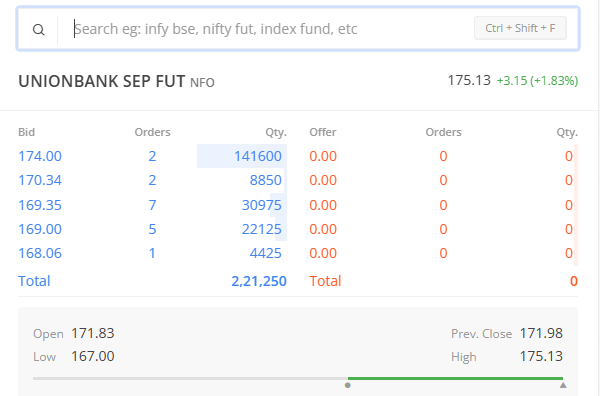
First counter to surprise was Union Bank, where Cash price after CAS was 166 but futures had buyer at 174, and not 1-2 buyer but buyer of 30 lots.
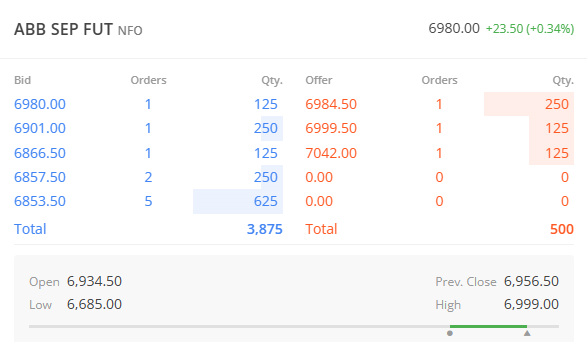
Next,shocking was ABB, in Final Cash price was 6660 from 6856, but september futures, they were smoking next level drugs, look at the market depth attached, there was a buyer at 6980. A 320 point or nearly 5% difference between cash and future option who is going to expire same day. Same with Solarindus, where around 2-3% difference was there.
Infosys, an index stock, didn’t moved. Cash levels rose to 1015 from 995, but futures remained around 1000 even till 3.40pm. Similar with HAL, IRFC, Cochin Shipyard and many more
If that is the case, then CAS is surely a trash for stock F&O. If such crazy shit is going to happen, the instead of physical settlement, cash settlement should be there for Stock F&O. There are arbitraeg opportunities but cannot use it.
Really interesting observation. I also feel CAS has created a genuine disconnect between the cash and F&O markets, especially in those last few minutes. The kind of price gaps you’ve pointed out can definitely make convergence and settlement more complicated.
This is something most of us may not notice unless we actually track the prices closely. NSE should look at synchronising the closing timings of cash and F&O, or at least review how the final settlement price is arrived at.
I think the situation in Union Bank and ABB is normal, bcz the CAS closing price may not necessarily the “true” closing price.
In both cases, the bid/ask levels in the market depth were broadly around the reference price. For 174 bid in Union Bank ,there could be several reasons for such an order for example, someone who had shorted fut and don’t want to get into the physical delivery, or someone trying to square off/net a position related to options.
If ABB has closed at ₹6,660 through CAS and someone is still willing to buy the future at ₹6,980 till 3:40, there has to be some reason for that bid.
The thing is once CAS is over, you can’t go and buy ABB at ₹6,660 anymore. So the normal cash-futures arbitrage isn’t really available after the price is known.
Maybe that’s why SEBI is already looking at this exact issue and has proposed either a blended CTS + CAS VWAP or, as an interim option, going back to CTS VWAP for expiry settlement.
Would be interesting to see the actual trades in those last 5 minutes rather than just the order book. That would tell us whether this was a genuine dislocation or just orders sitting there.