Hello and welcome to the Weekly Market Metrics! I’m Sandeep Rao, and we’re now in Week 19 of 2026.
The week started with a massive political shake-up as the 4 May Assembly Election results saw the BJP making history in West Bengal, actor Vijay’s TVK party stunning everyone in Tamil Nadu, and the UDF sweeping back to power in Kerala.
Looking at the world at large, it’s now been a little over two months since the Iran conflict began, and there still doesn’t seem to be any clear resolution in sight. Every now and then, we get to hear about talks of a ceasefire, but as of yesterday, the situation still appears to be in limbo. Jerusalem Post — Iran Update
And if that wasn’t enough, the S&P 500 and the Nasdaq Composite are both hovering close to their previous all-time highs — largely driven by a handful of major technology stocks — while our Nifty 50 still remains roughly 8% away from its highs.
So for us, it’s a bit of a double whammy. Not only are our markets struggling, but we’re also not insulated from the second-order effects of the war — whether through commodities or currency. And on top of that, international ETFs listed in India continue to trade at fairly steep premiums, thanks to the overseas investment limits imposed by the Reserve Bank of India.
But as always, not everything is bad. There are still pockets of strength within the market — sectorally, there are areas that continue to hold up well, and those are some of the things we’ll explore as we go through this weekly update.
Section 1 — What Happened Last Week
Rate of Change (ROC) Across Indices
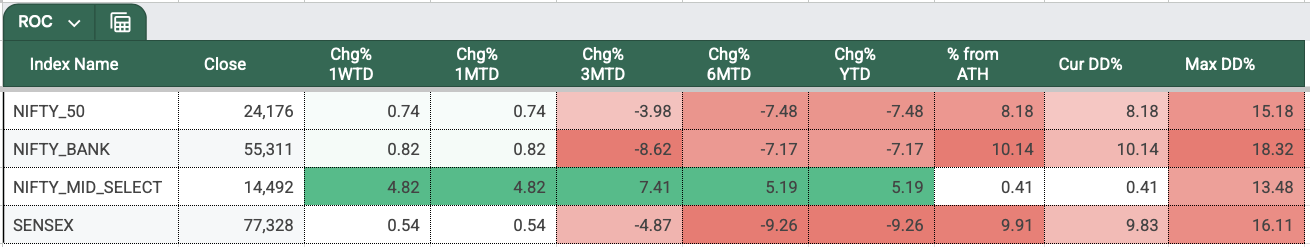
Very similar to last week, this week was muted for Nifty, Bank Nifty, and Sensex, which gained between 0.5% to 0.8%. The standout performer was Midcap Nifty, which gained 4.82% and made a new all-time high (ATH) this week. The other three indices are still 8–10% away from their previous ATHs.
On a YTD basis, only the Midcap Nifty is in positive territory. Not just this index, but the Nifty Midcap 100 also made a new ATH this week. Maybe investors are betting on midcaps over large caps in the current scenario — a reminder of the importance of being well-diversified across market caps. If you know the reason, do let me know in the comments.
NIFTY
Weekly
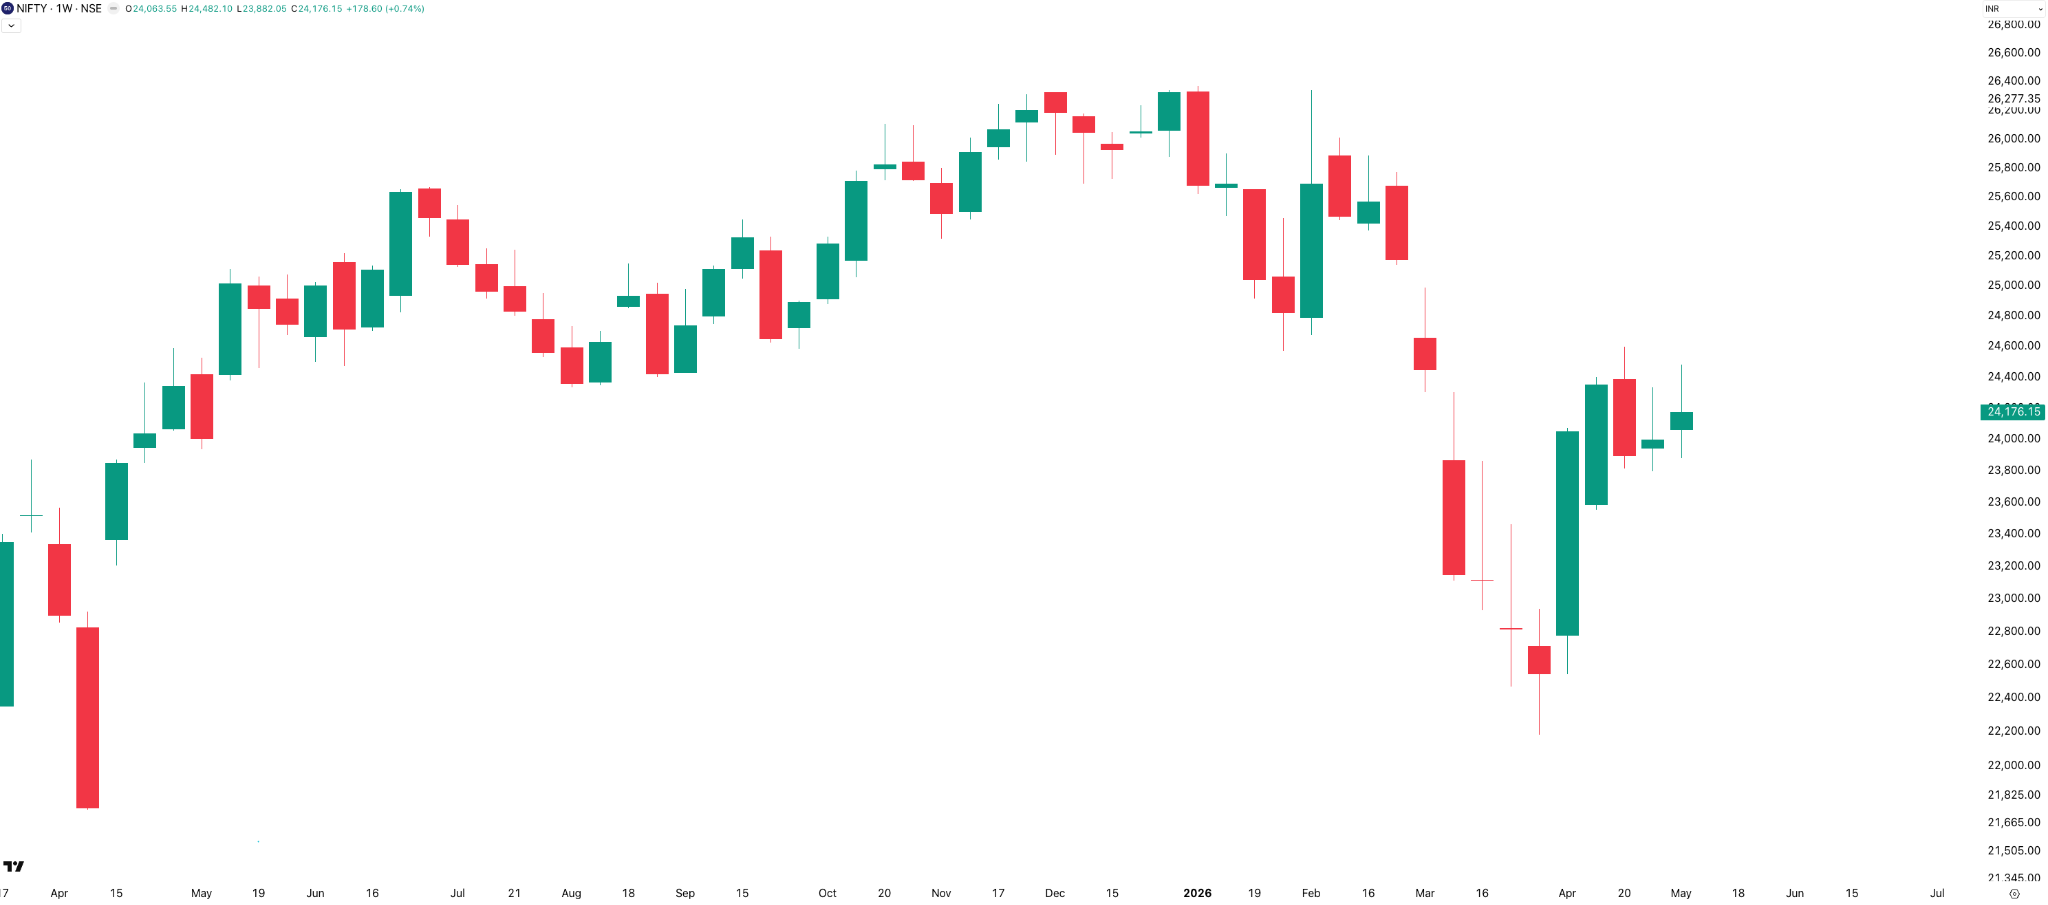
Last week Nifty made wicks on both sides of the weekly candle. This week as well, Nifty gained 0.74% or 179 points to close at 24,176 — again leaving wicks on both sides of the candle.
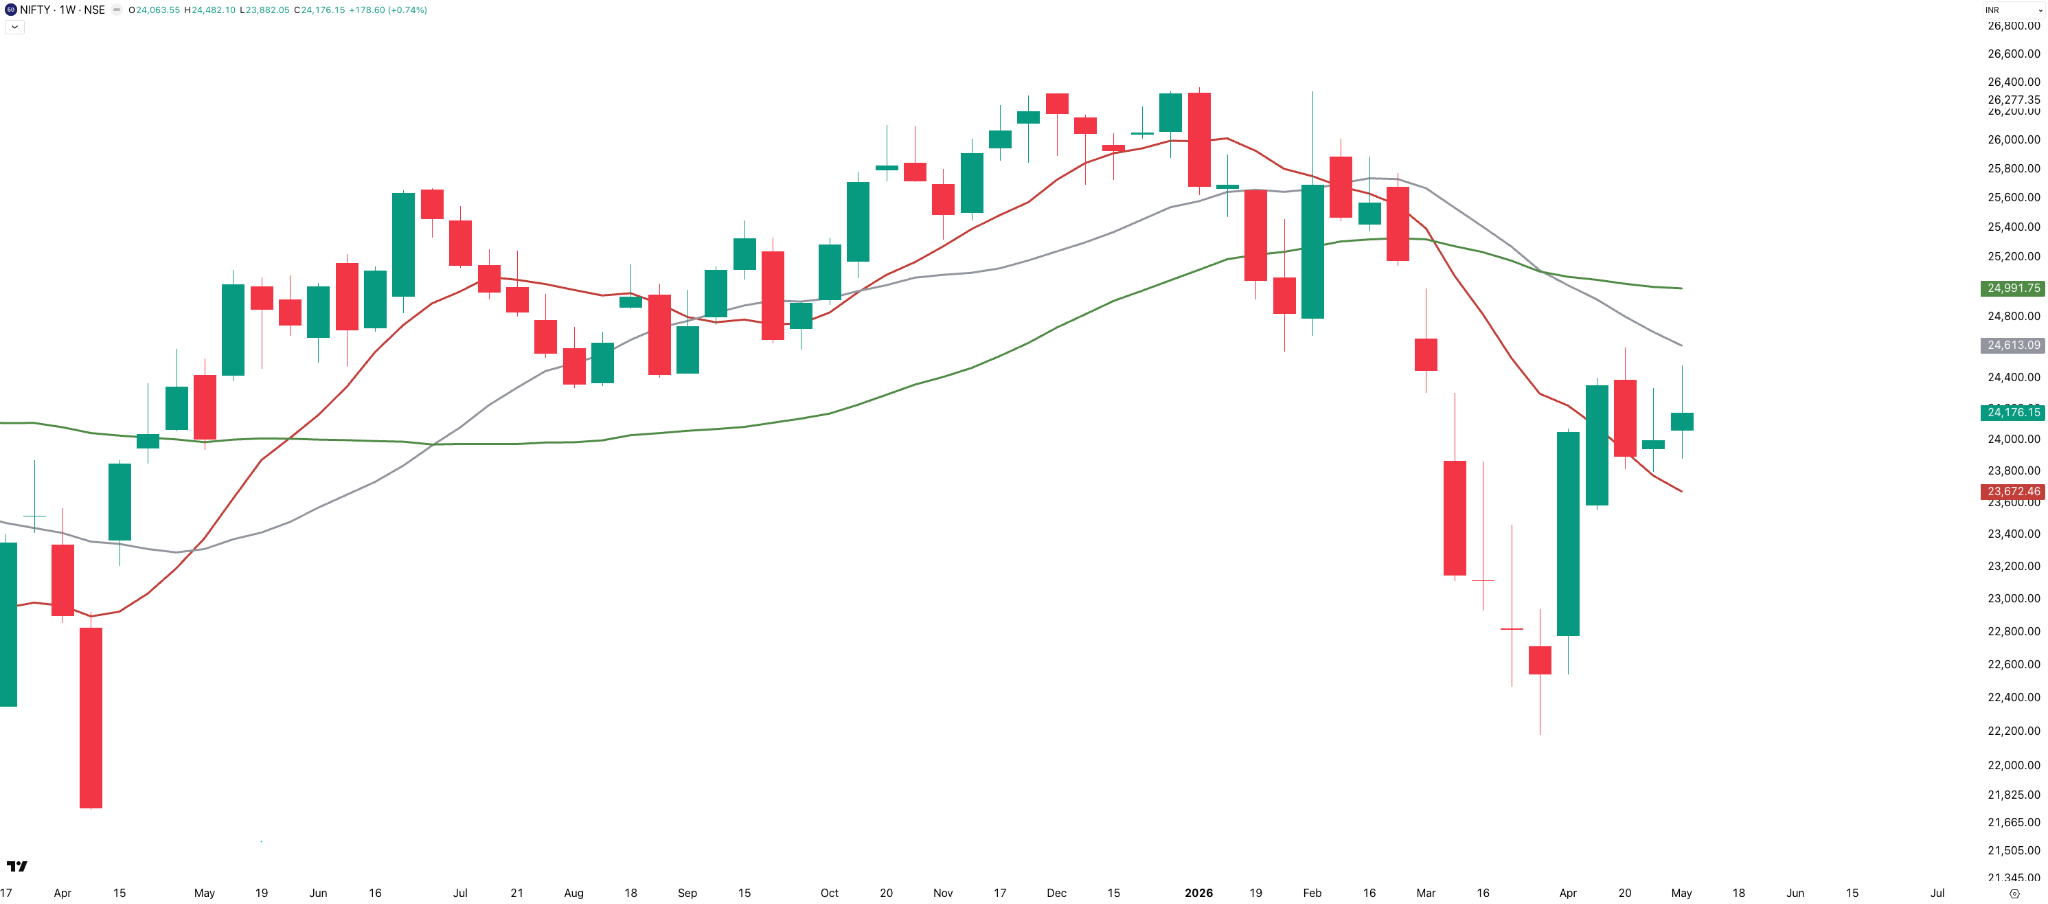
On the weekly timeframe, Nifty is trading above its 10-week SMA, but remains below the 20-week SMA and 40-week SMA, which are positioned at 24,600 and 25,000 respectively. These 10, 20, and 40-week SMAs are critical as they act as institutional benchmarks for short, medium, and long-term trends — prices staying below these levels typically means that the broader market bias remains under pressure.
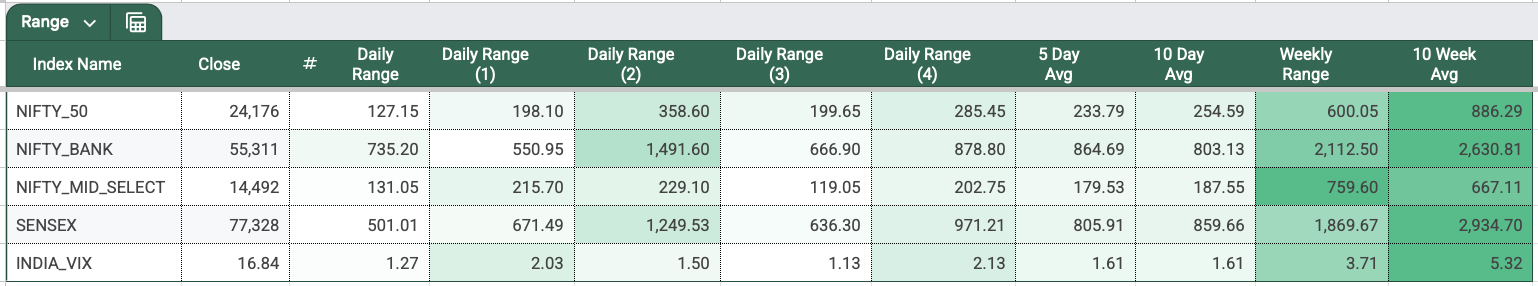
The weekly range was 600 points, slightly higher than last week’s 538 points. However, it’s worth noting that last week was only a 4-day trading week, while this week had all five full trading days. Wednesday saw the highest daily range at 359 points, whereas Friday saw the lowest at just 127 points. Such a narrow range on Friday is quite strange, especially considering the high number of volatile, wide-range Fridays we have witnessed in the recent past.
Daily
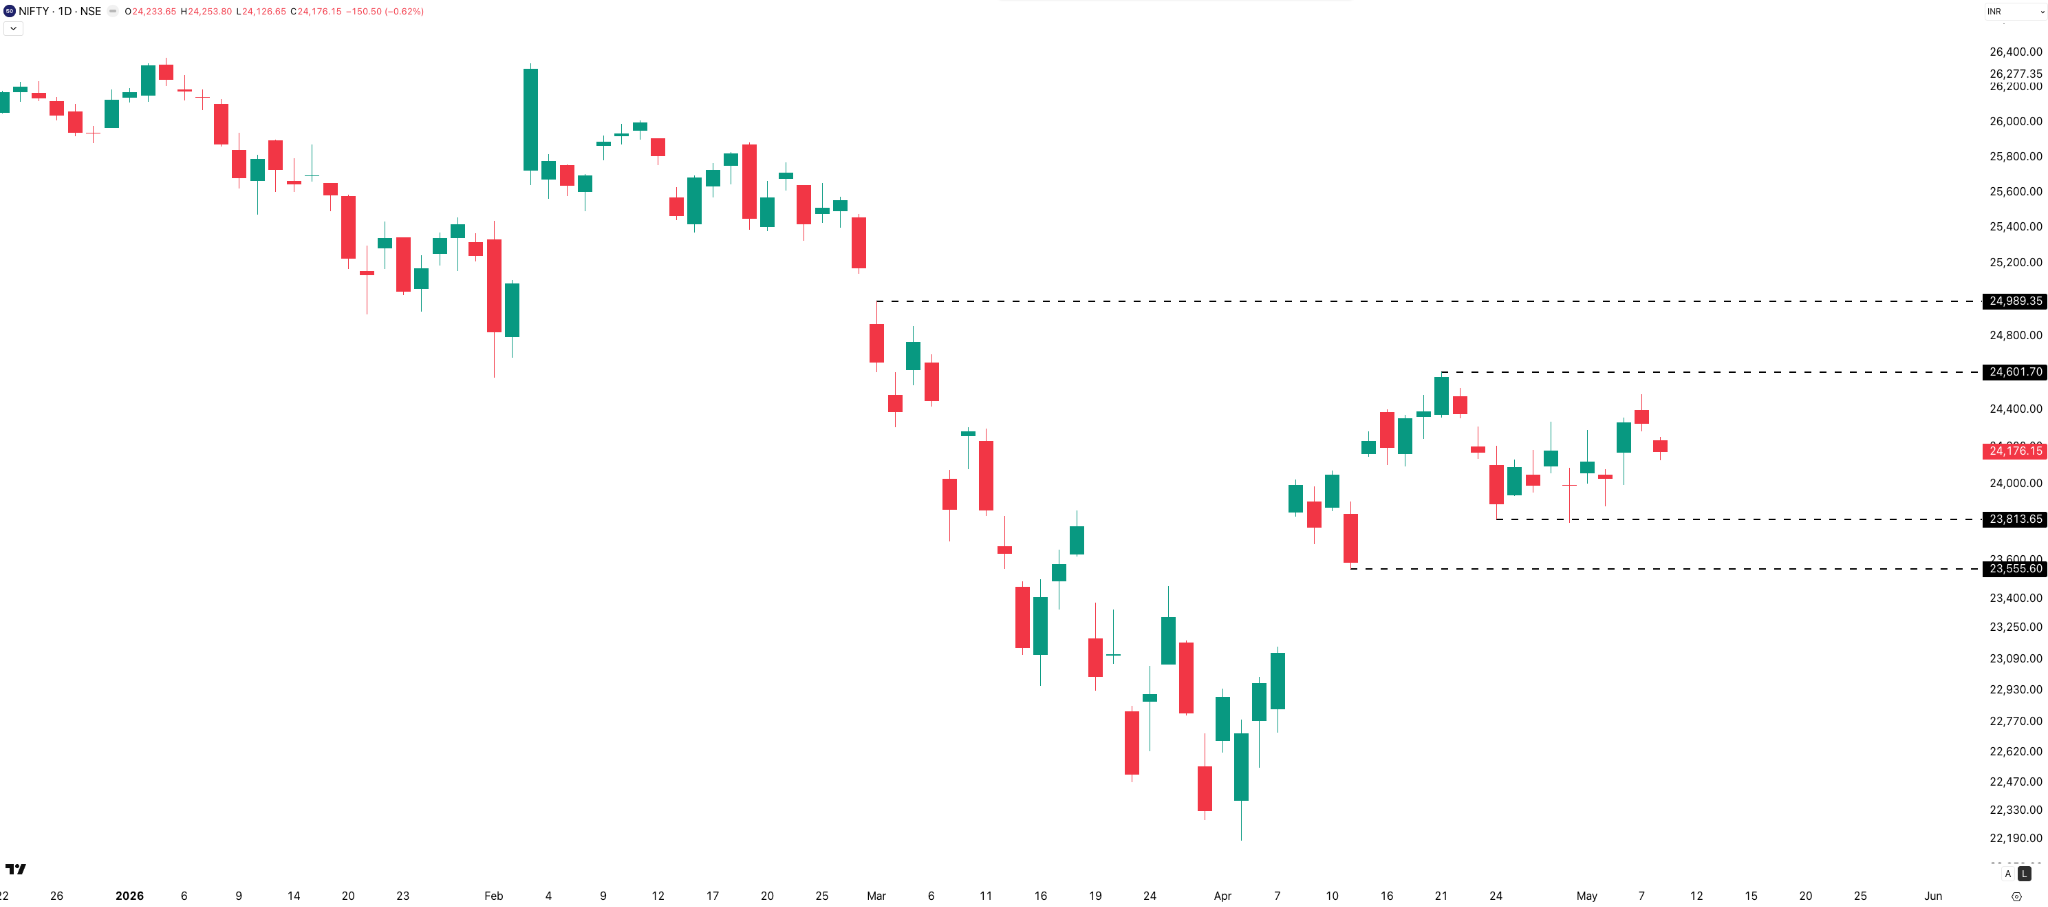
On the daily timeframe, Nifty has been stuck in a 1,050-point range between 23,550 and 24,600 for a month now, and the price action remains choppy. A sustained move — whether on the upside or the downside — will likely happen only once the index breaks out of this range.
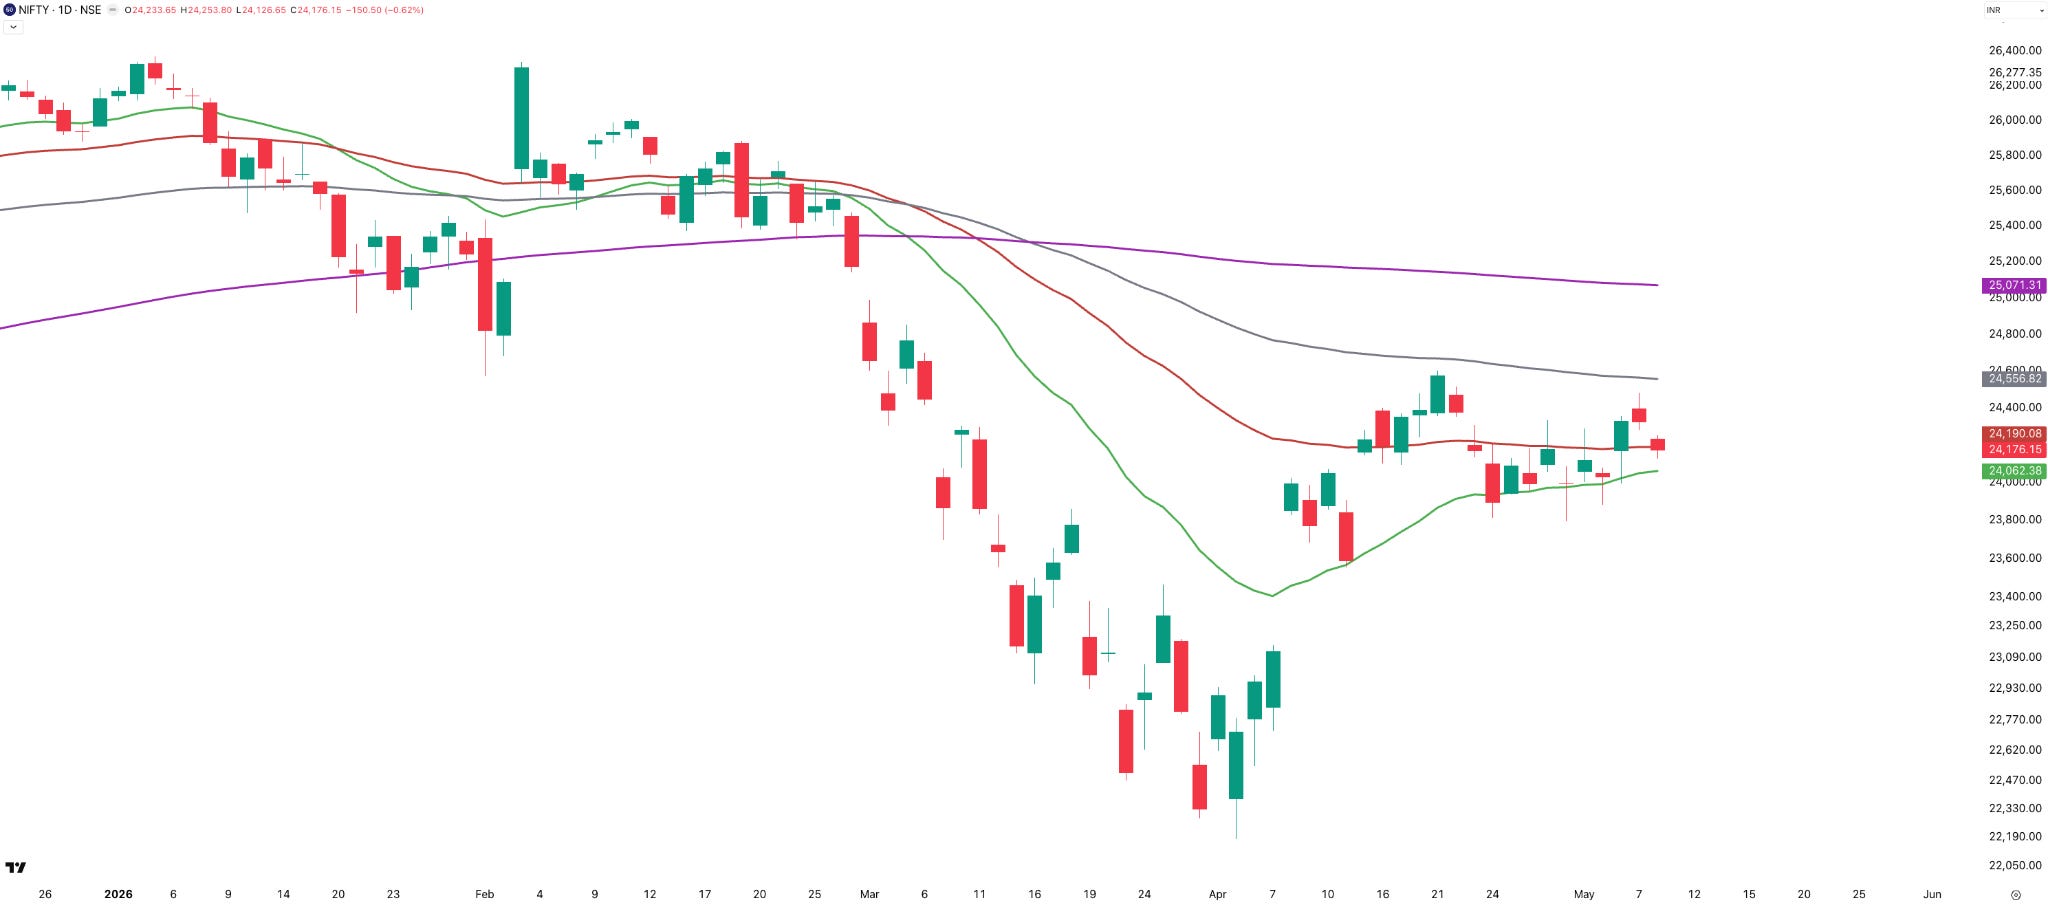
Currently, Nifty is trading above its 21-day EMA, while below the 50 EMA, 100 EMA, and 200 SMA. This structure tells us that the index is stuck in a range with a clear downside bias.
Hourly
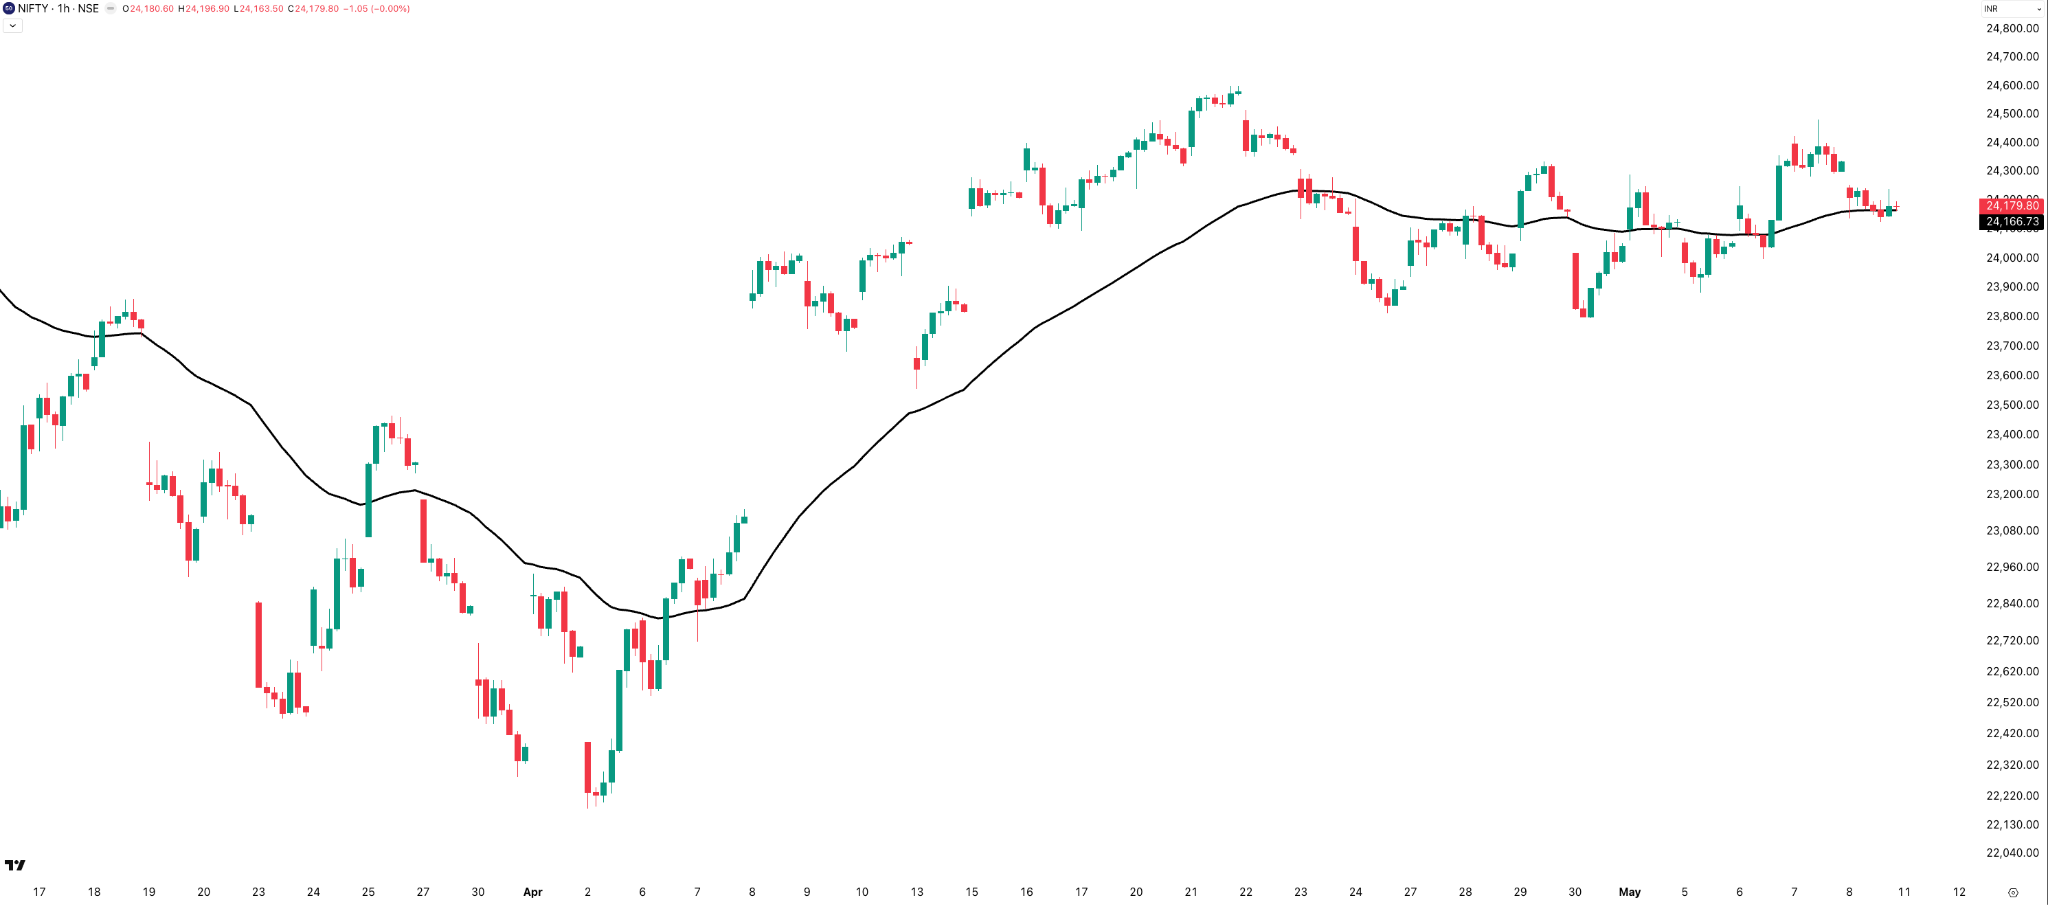
On the hourly timeframe, NIFTY is hovering around the 50 EMA, chopping through short-term trend followers and giving them “death by a thousand cuts.” Neither longs nor shorts are working right now. It reminds me of this meme:
There are two ways in which short-term trend followers can survive this environment: one is by having a good laugh, and the other is by keeping their position sizing in check.
If you have observed over the past week, almost every day saw a V-shaped recovery. The market either opens up or down, continues in that direction, and then suddenly makes a sharp move in the opposite direction. This suggests elevated levels of intraday volatility — but surprisingly, neither option premiums nor India VIX is reflecting that. It’s a strange disconnect where the price action is wild, yet the fear gauge remains completely flat.
Nifty Weekly Expiry — Tuesday, 5 May
The expiry had a range of only 199 points — even lower than the previous expiry’s range of 221 points. At first glance, one might think this would have been an easy day for option writers, but the opening straddle premium was a mere 138 points. The index then proceeded to move down 200 points before recovering those same 200 points. It was anything but an easy expiry for option writers. On the flip side, option buyers might have actually found some opportunities in those swings — if you were one of them, let me know in the comments.
Section 2 — What to Expect in the Coming Week
NIFTY
Nifty is stuck in the range of 23,550 to 24,600. Unless the index breaks out of this range, expect more consolidation or choppy price action to continue. What will help the index break out? Maybe some definitive news on the Iran conflict front. Other than that, there don’t seem to be any standard support or resistance levels that will do the job, at least in the near future.
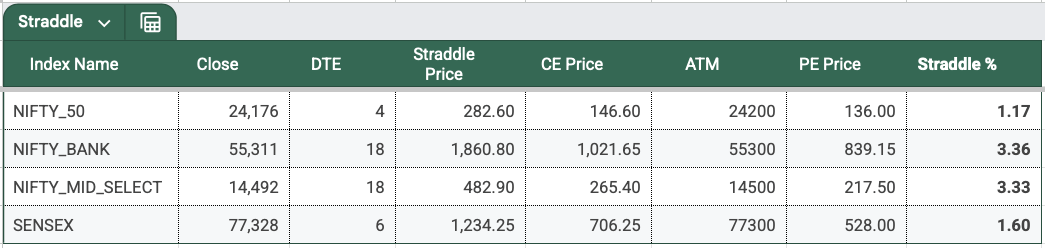
The Nifty straddle has closed at 283 points, implying a move of roughly 1.17% on either side. But as we have seen over the past many weeks, this is largely overnight risk premium that melts right at the open — and we hardly see any decay during the day. Let’s see if this weekend is any different. The expected range as per the straddle chart comes to 23,900 to 24,450 for the upcoming weekly expiry on Tuesday, 12 May .
The overall bias for Nifty is still sideways to bearish . Until the index breaks out of the 1,000-point range it is stuck in, not much is expected to happen. We need some catalyst to make that move occur — let’s see what that will be and how soon it happens.
Directional Bias Summary
The primary update this week is that the short-term bias for Sensex has shifted:
- Nifty and Sensex: Short-term bias is now positive, while medium-term remains negative. Nifty and Sensex have closed back above their 21 EMA on the daily timeframe, signalling a potential recovery in immediate momentum.
- Bank Nifty: Both short and medium-term biases remain negative, reflecting its ongoing relative weakness.
- Midcap Nifty: Continues to be the outlier with both short and medium-term biases remaining positive, consistent with the strength seen last week.
India VIX
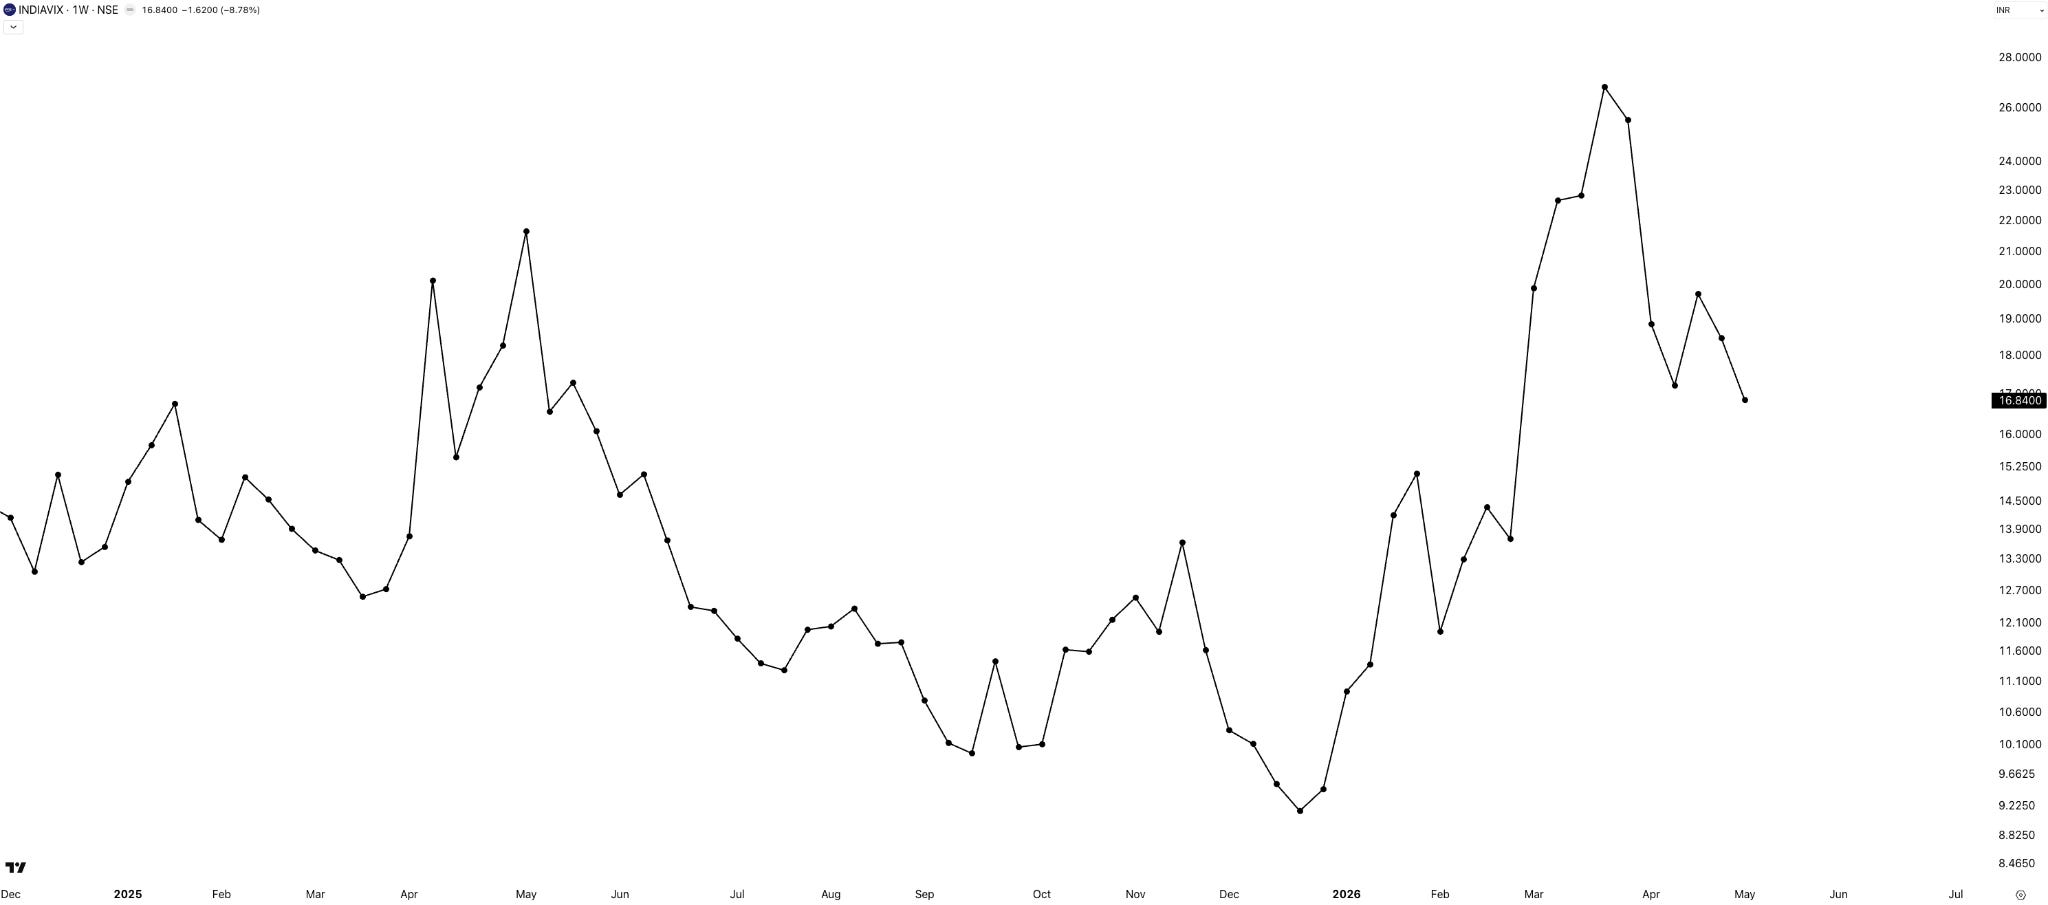
India VIX fell 9% this week to close at 16.84. While this fall is in line with the contracting daily ranges, it stands in stark contrast to the intraday volatility — which remains through the roof.
Sectoral Performance — Tijori Indexes (TJI)
For those who’ve been following for the past few weeks, you know the system — 82 granular sectoral indexes in Tijori, making it far easier to spot pockets of strength, especially for stock picking.
This week’s top five performers: Wires & Cables, Microfinance, Communication Equipment, Diagnostic Chains, and Packaged Meat. Almost no overlap from last week’s indexes. Last week’s standouts — Transformers and Upstream — both seem to have taken a pause this week.
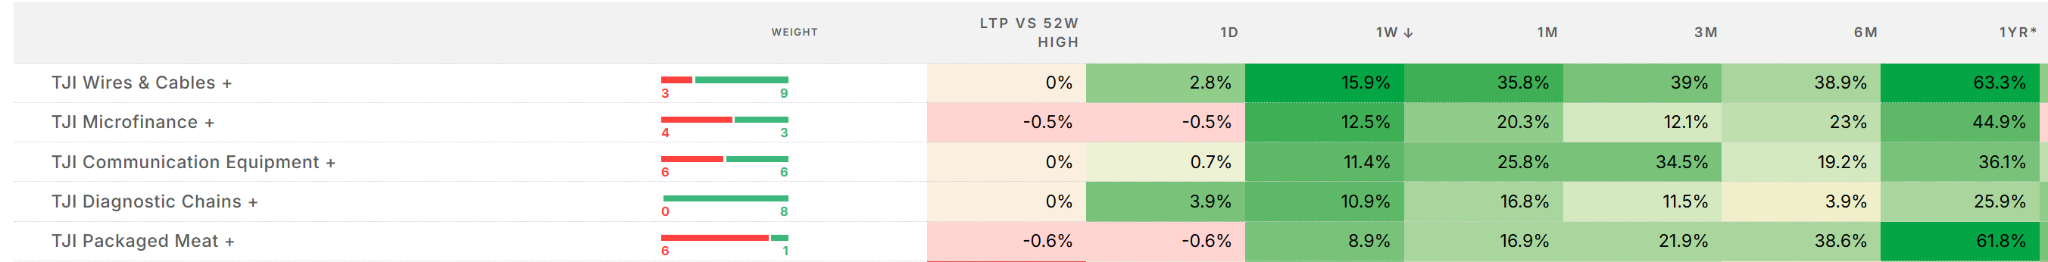
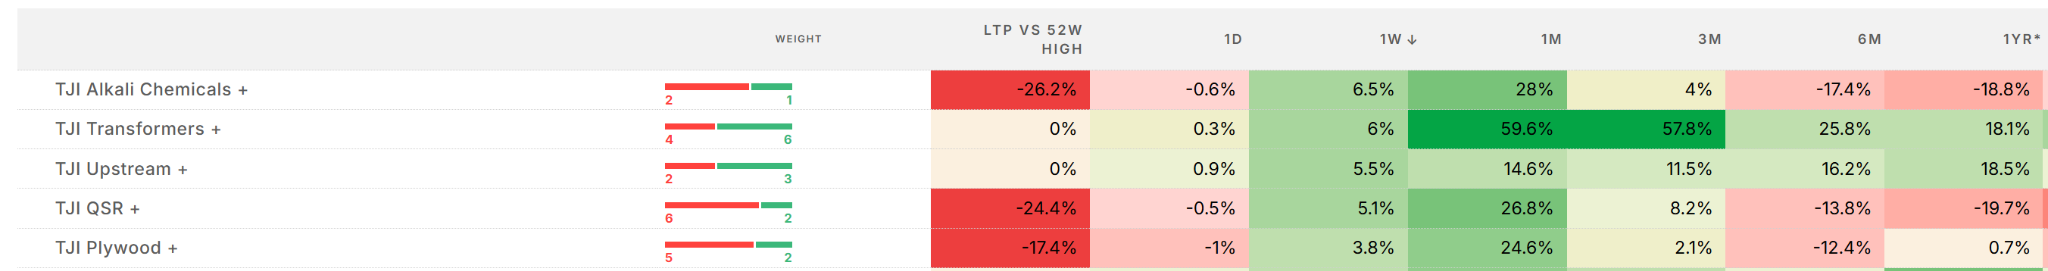
Looking at the 52-week high view — sectors closest to their 52-week highs or making new ones — last week we had just four such sectors: Transformers, Defense, Refractories, and Upstream. This week, we’ve got 10 of them. At a very fundamental level, this talks about the increasing breadth of the market, which is obviously a good sign. And do notice the fact that while Nifty50 is stuck in a range, some niche sectors are making all-time highs.
Wires & Cables is the clear standout — up nearly 16% in just seven days, and 63% over the past year. A few things seem to be happening simultaneously here. On the power side, electrification is happening at scale — both renewable and non-renewable — driving massive investments in transmission and distribution infrastructure. Then you have the railways pushing full network electrification, which requires enormous quantities of cables across thousands of kilometres of track. And on top of that, 5G rollout, data centres, and urban infrastructure are all adding to the demand. In a way, this sector is benefiting not from just one wave but from multiple macro factors simultaneously.
Defence is another sector worth paying attention to — up close to 68% over the past year and sitting right at its 52-week high. The story here is fairly straightforward: the government has significantly stepped up its defence budget, and a growing share of that procurement is now being directed toward domestic manufacturers. More money is flowing into these companies, and the stock prices are reflecting that.
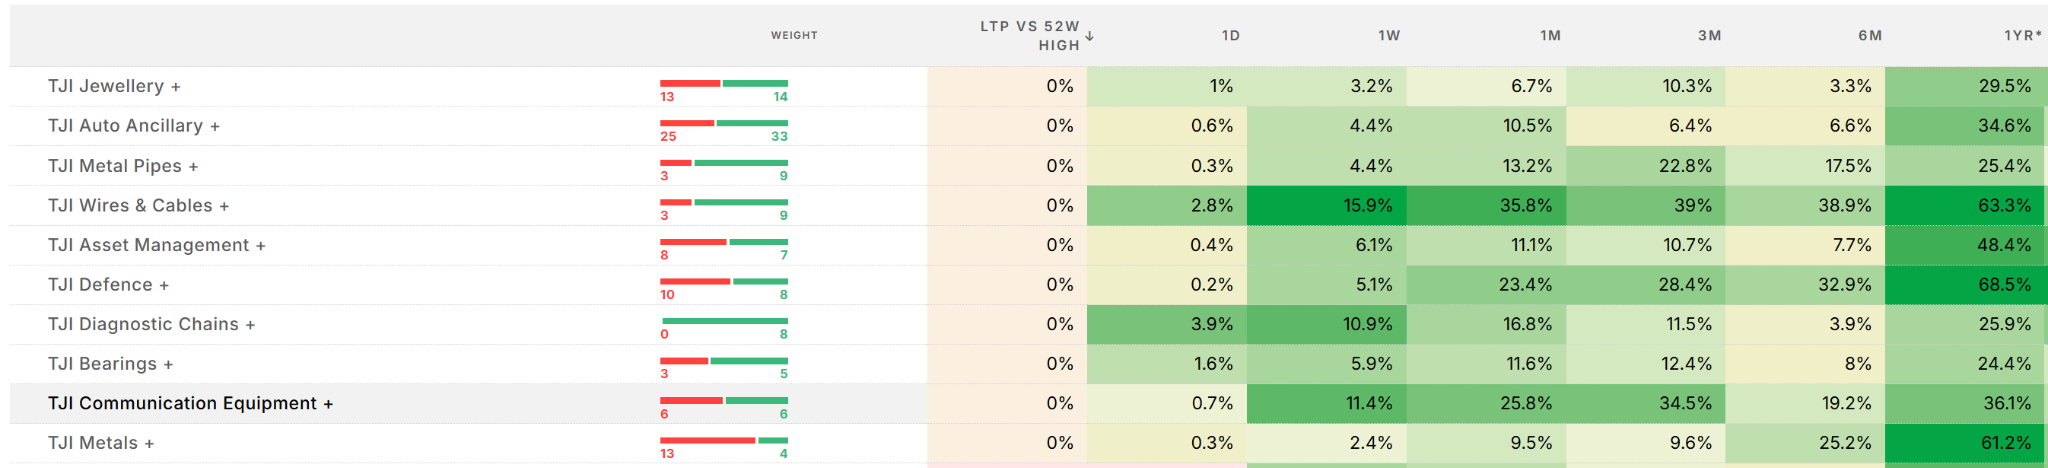
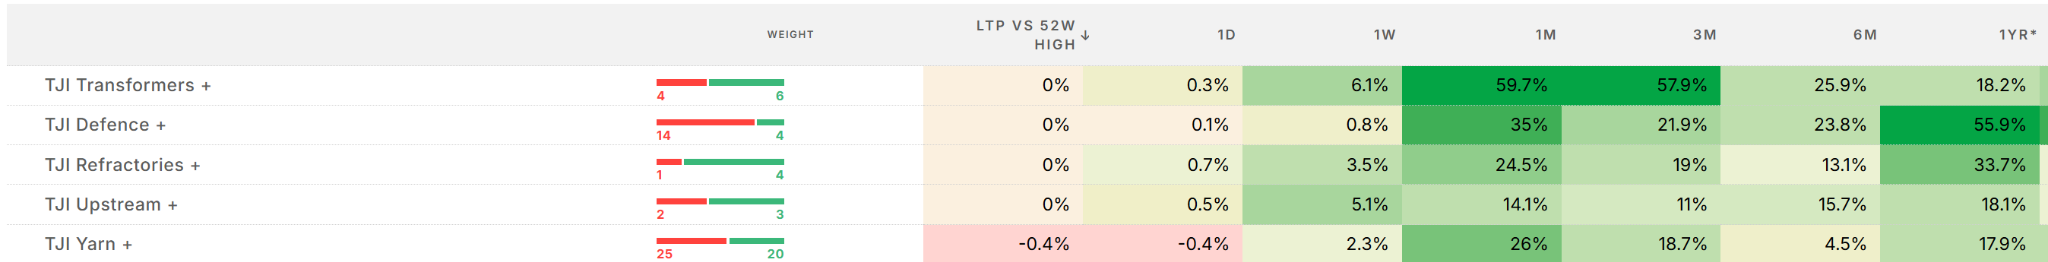
As always, it’s a great idea to double-click on these sectors and understand the stocks that are leading within them before taking a call.
Commodities
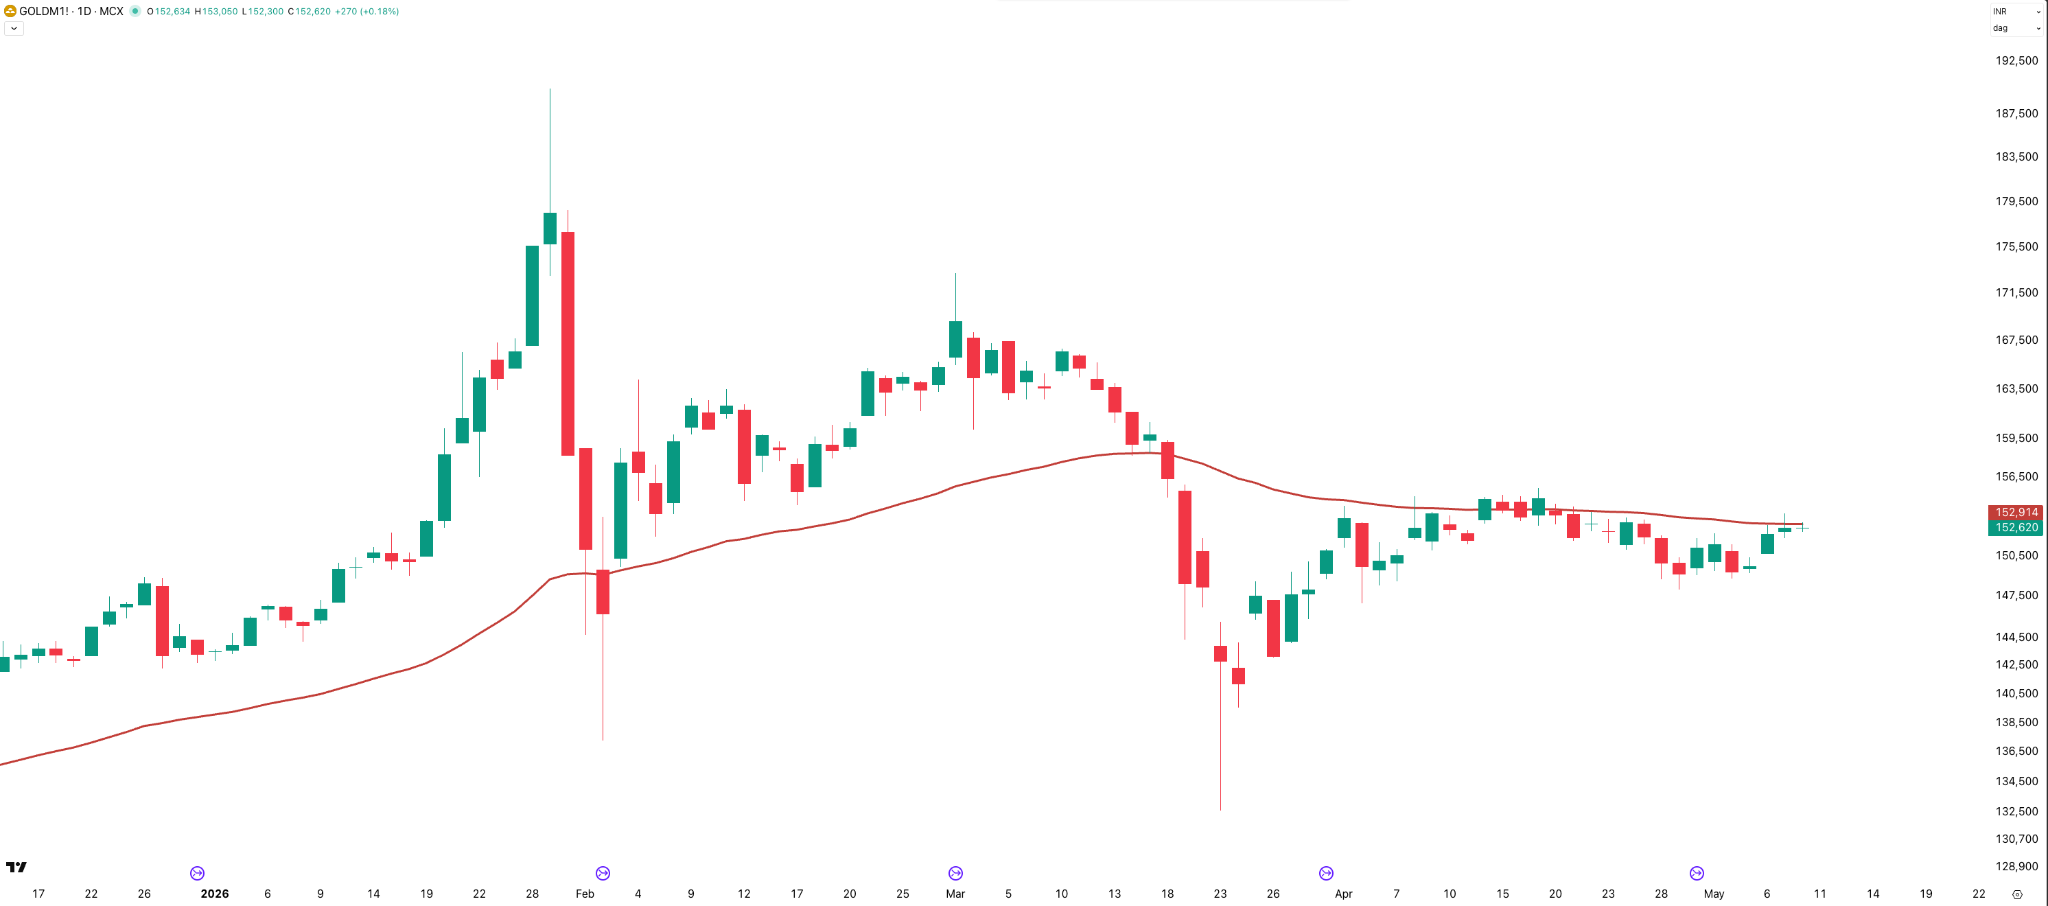
Gold was up just about 0.9% for the week, and Silver was up about 4%, with Copper also around 3%. On a daily timeframe, Gold futures are hovering around the 50 EMA, and Silver futures are just above it.
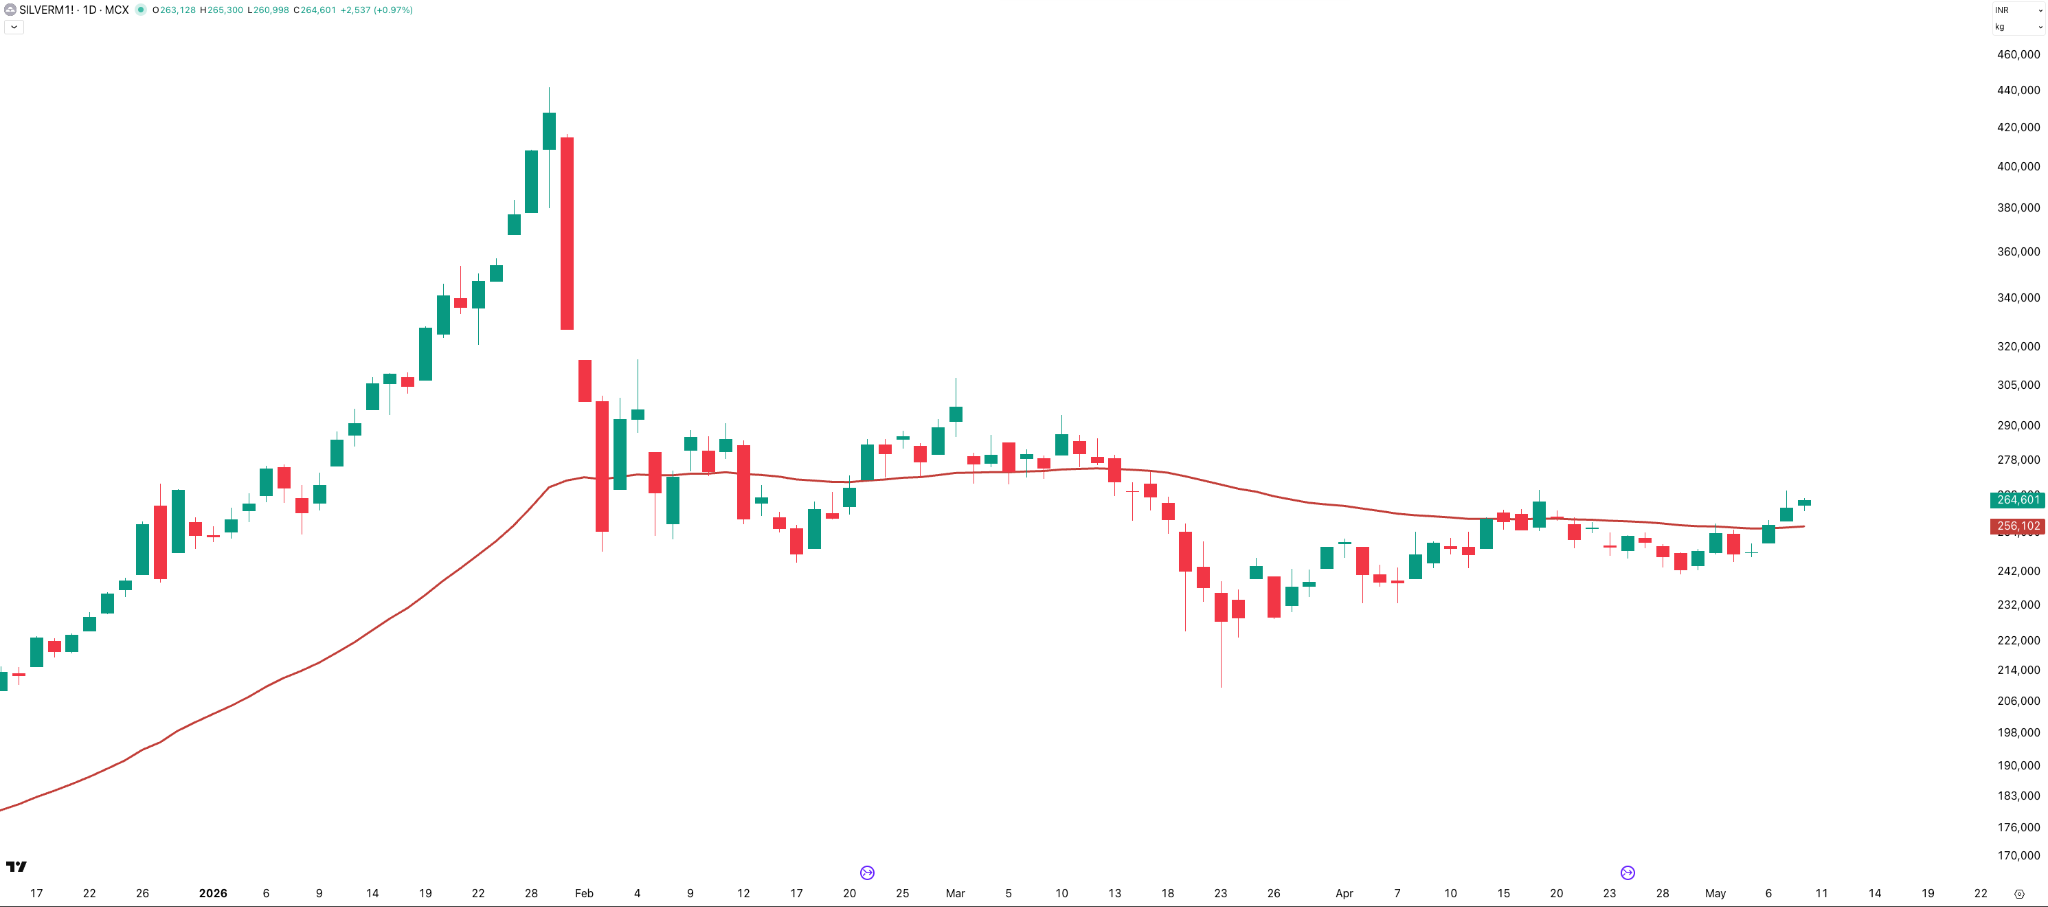
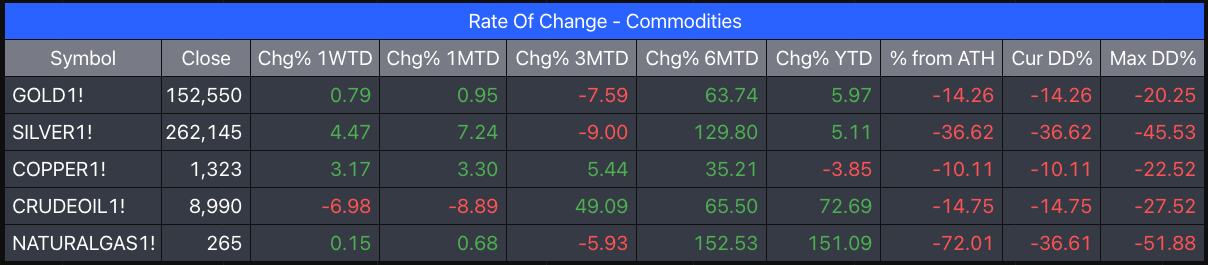
Crude oil, on the other hand, is cooling off. It had run up to close to $112, but with ceasefire talks gaining some traction, we’re seeing a minor pullback. It’s not like crude is heading back to the $60–70 range anytime soon, but the immediate pressure seems to be easing a bit.
Natural gas has been largely flat — no major moves there for now.
Summary
Markets moved into a holding pattern this week. While Nifty, Sensex, and Bank Nifty posted modest gains, the real story was the massive 5% surge in Midcap Nifty, which made yet another all-time high.
Nifty and Sensex are showing indecision as they hover around key moving averages, and Bank Nifty continues to underperform. The weirdest part? Even though the VIX crashed 9%, the intraday action was absolute chaos. Those sharp V-shaped recoveries meant that even though the daily range looked small, the choppy price action was enough to give trend followers and short-vol traders sleepless nights.
Sectoral strength is widening — a good sign — with 10 sectors now near their 52-week highs. Wires & Cables and Defence are the clear standouts to remember.
The bottom line on Nifty: we’re stuck in a sideways grind with a slight bearish tilt. Until we get a definitive catalyst to break this 1,000-point range, expect the indecision to continue.
What Caught My Attention This Week
Watch/Read: Last week, CNN founder Ted Turner passed away at the age of 87. He was a pioneer of cable news and specifically the 24-hour news format that we take for granted today. If you’re the watching type, Call Me Ted — a 2024 six-part documentary series — chronicles the life of the media mogul: his career, his interest in sailing, the launching of 24-hour news, and a bit of his personal life. There’s also a book by the same name if you’d prefer to read.
Read: An Aeon article about Ethiopian runners — What Ethiopian Running Says About the Limits of Human Ability. The piece focuses on two different approaches to marathon training: the very personalised, Western, data-oriented individual approach versus the Ethiopian approach, which is more collective and more human. While it’s about running a marathon, it made me think about how we look at markets as well.
Events to Factor In
- Tuesday, 12 May — April CPI Inflation (Consumer Price Index) data release
- Thursday, 14 May — WPI Inflation (Wholesale Price Index) data release
You can track the economic calendar and major upcoming known events on Zerodha.
If you find this series useful, don’t forget to subscribe to the channel — and do share it with your friends.
Until then — stay curious, stay steady, and enjoy your weekend.