Hello and welcome to the Weekly Market Metrics! I’m Sandeep Rao, and we’re now in Week 25 of 2026.
Remember last week’s Iran rollercoaster? This week, the deal actually happened. Signed on Wednesday, the naval blockade lifted Thursday, the Strait of Hormuz back open for business. But “happened” doesn’t mean “settled.” Iran’s Supreme Leader Mojtaba Khamenei broke his silence to say he’d personally disagreed with the deal but let it go ahead — and that Trump struck it “out of desperation.” And now the real fault line has shifted to Lebanon. So while oil is flowing, the situation is still not sorted yet.
While everyone was watching Iran, the RBI quietly made what could be its biggest currency move since the 2013 taper tantrum playbook. Two new swap facilities were announced — one for NRI dollar deposits, one for foreign borrowings — letting banks bring dollars into India at zero hedging cost, with the RBI absorbing all the currency risk. Back in 2013, a similar but costlier version of this scheme brought in $34 billion and helped the Rupee recover. This one is more generous, and the RBI is betting it brings in $40 to $50 billion this year.
Markets seemed to like the combination. Nifty closed the week above the 24,000 mark, and India VIX cooled off below 13.
Section 1 — What Happened Last Week
Rate of Change (ROC) Across Indices
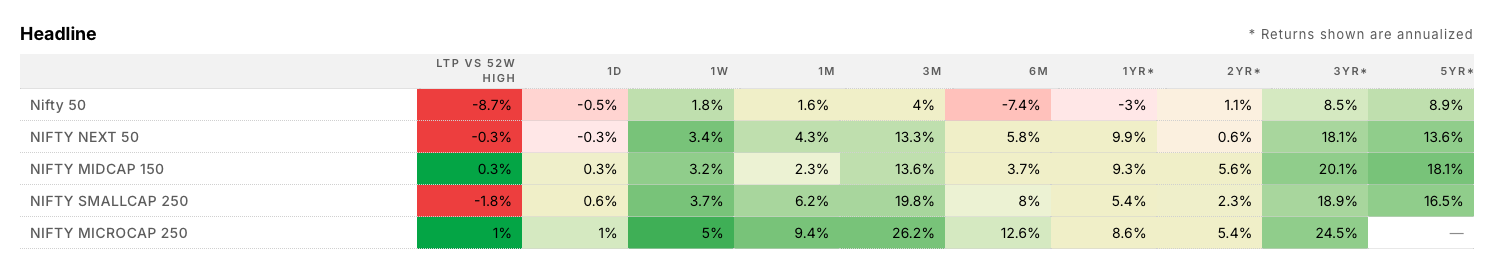
A good week across the board. Nifty 50 gained 1.8%, but unlike last week, it wasn’t carrying the market alone. Next 50, Midcap 150, Smallcap 250, and Microcap 250 all joined the party, gaining between 3% and 5%.
On 3-month returns, Microcap 250 continues to lead at 26.2%, while Nifty 50 remains the lowest at just 4%. Despite Nifty 50 still being down 7.4% over the last six months, every other index is comfortably in the green. It’s almost as if there are two markets running side by side — the one everyone talks about, and the one actually making money.
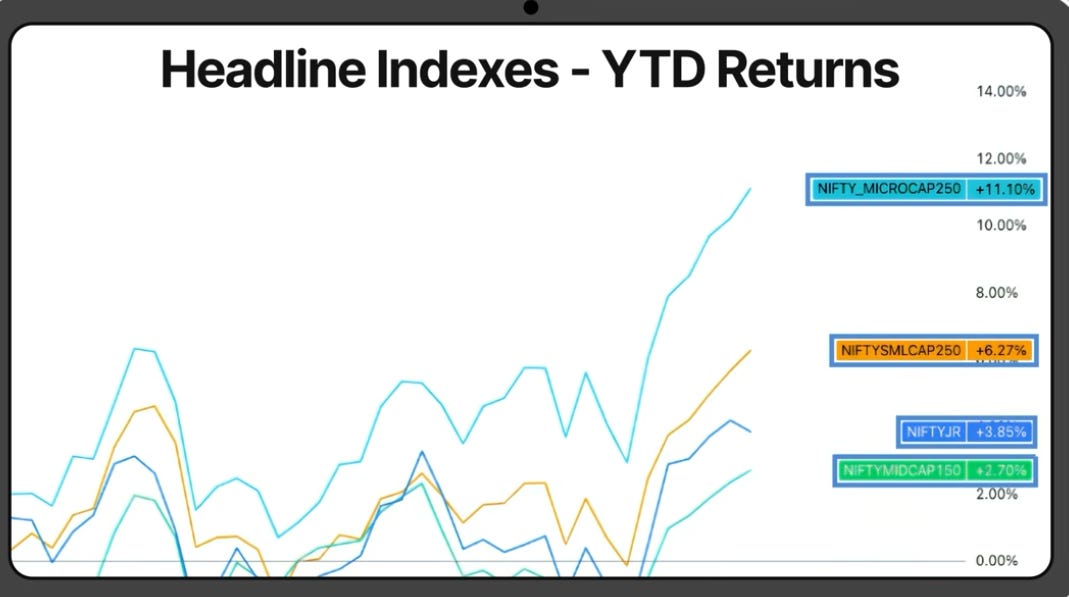
If we look at the YTD numbers, MICROCAP 250 again leads the pack at 11.1%, followed by SMALLCAP 250 at 6.3%. NEXT 50 and MIDCAP 150 are now back in the green at 3.8% and 2.7% respectively, while NIFTY 50 remains the clear laggard at -8.2%.
On YTD numbers, Microcap 250 leads at 11.1%, followed by Smallcap 250 at 6.3%. Next 50 and Midcap 150 are now back in the green at 3.8% and 2.7% respectively, while Nifty 50 remains the clear laggard at -8.2%. We’re almost halfway through 2026, and the story remains the same — the broader market continues to outperform the headline index.
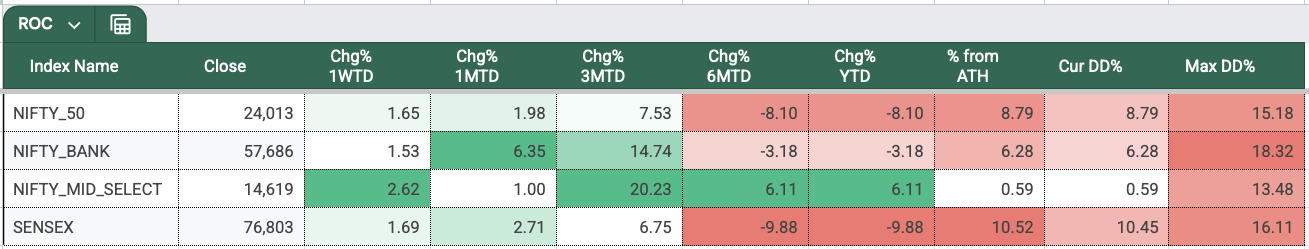
Nifty Mid Select stands out again this week — up 2.6% for the week, 20.2% over the last three months, and still the strongest index on a YTD basis at 6.1%. Nifty Bank continues to hold up well too, gaining 1.5% this week and 14.7% over the last three months.
NIFTY
Weekly
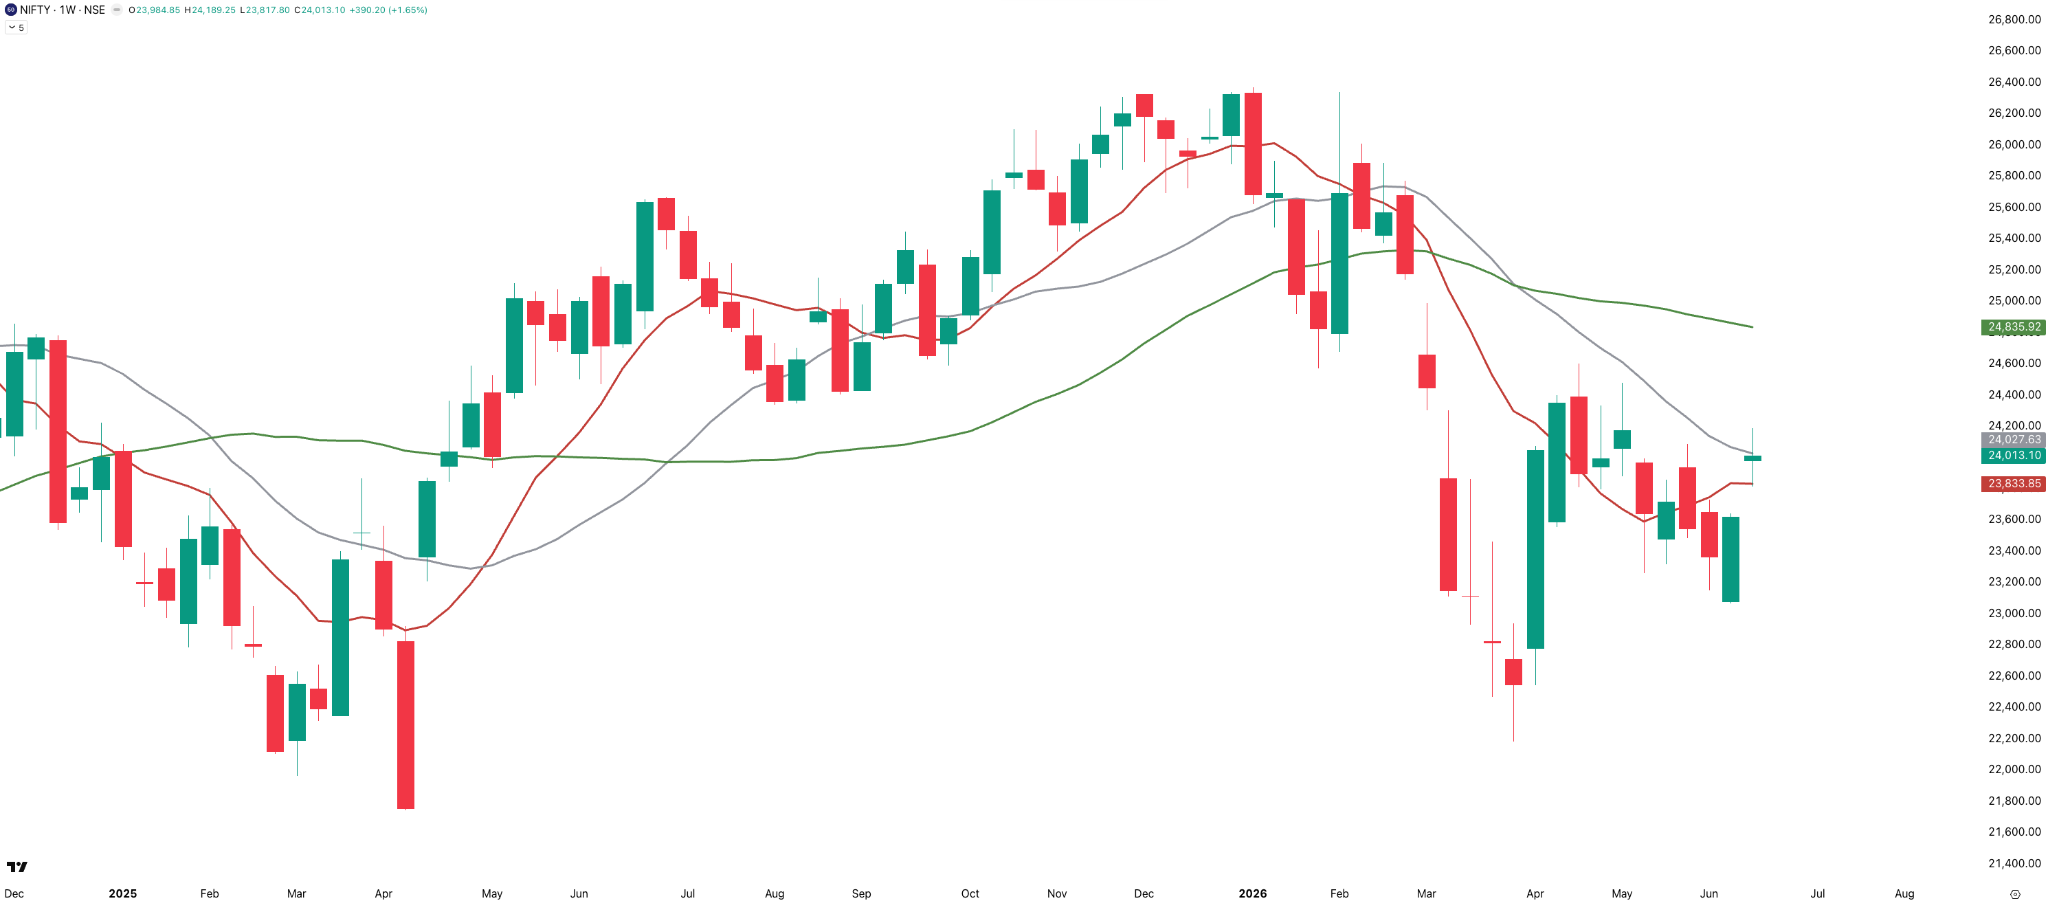
This week, Nifty gained 390 points, or 1.65%, to close at 24,013. It continues to trade above the 10-week SMA and is now very close to reclaiming the 20-week SMA as well.
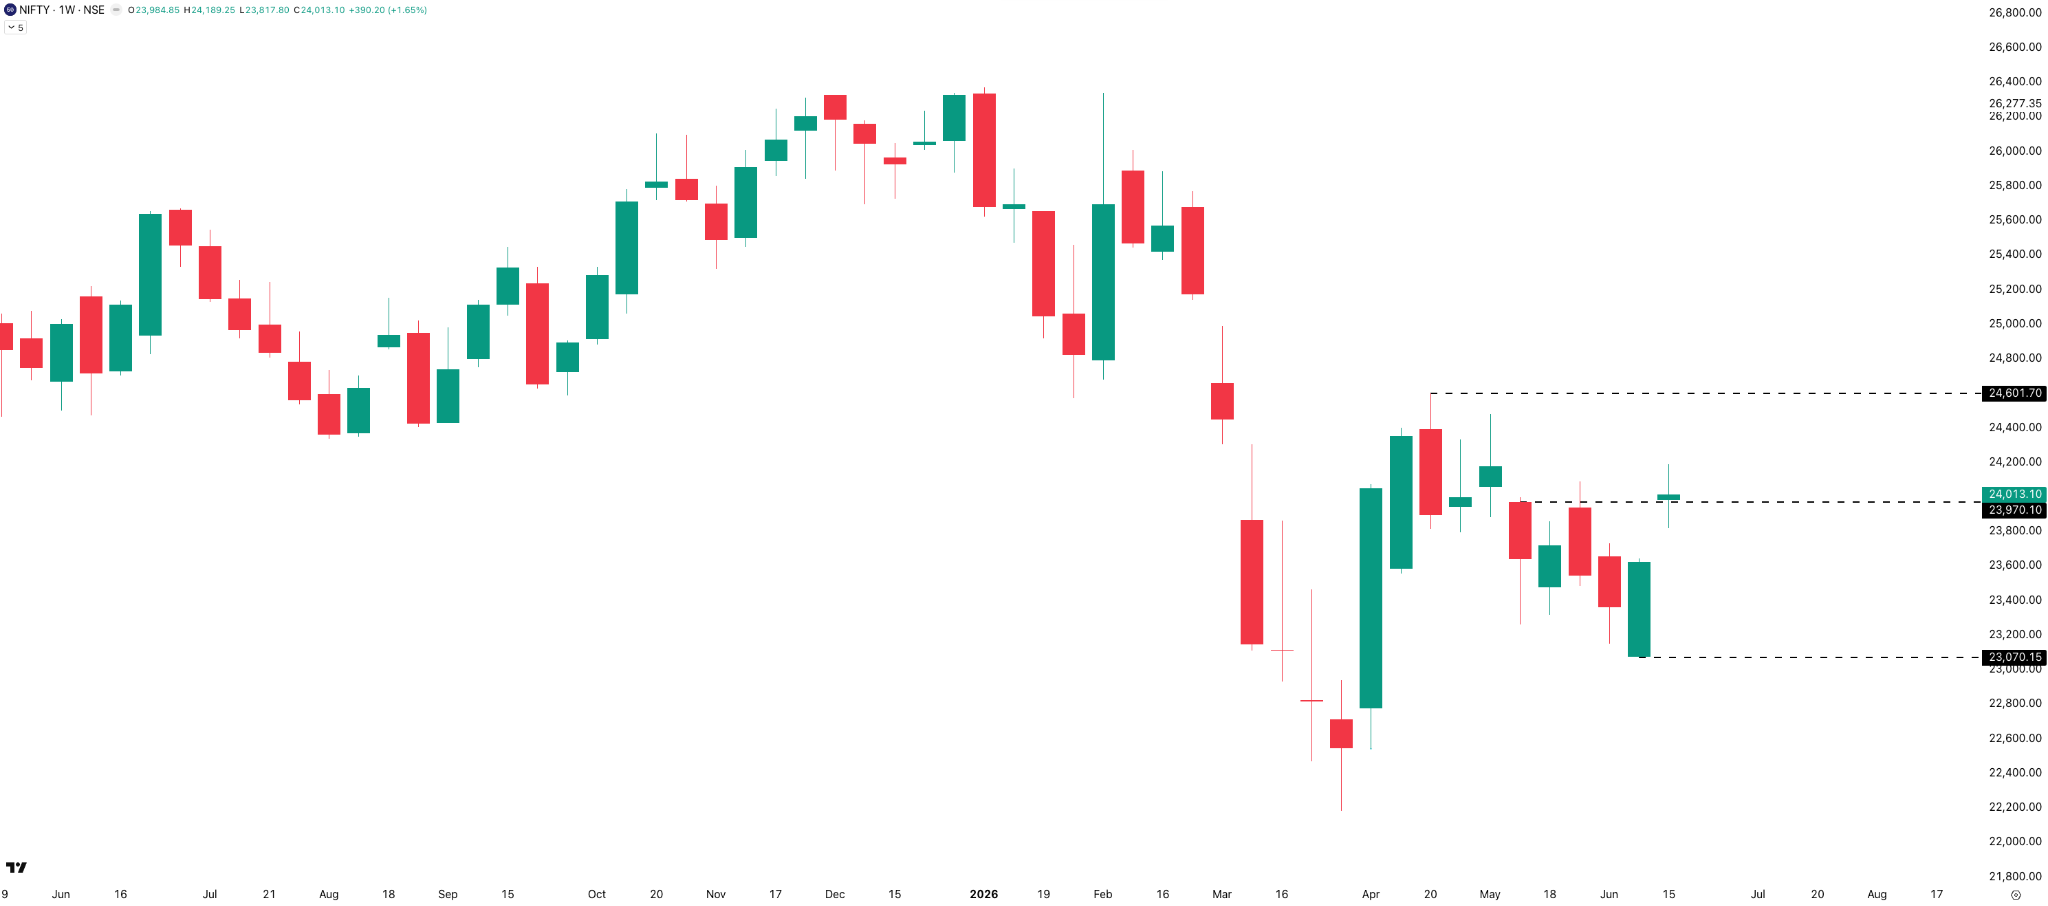
Nifty is now trading above the previous resistance of 24,000 and has moved back into the 24,000–24,600 range.
W25
W24
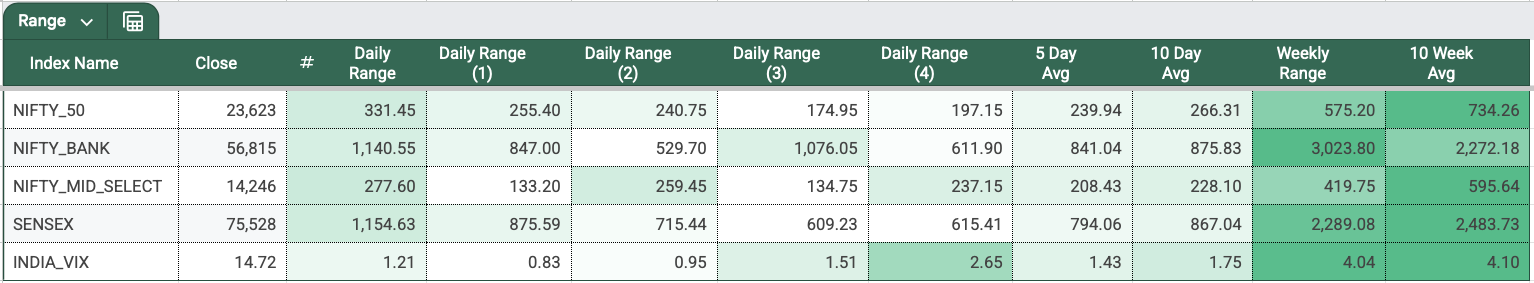
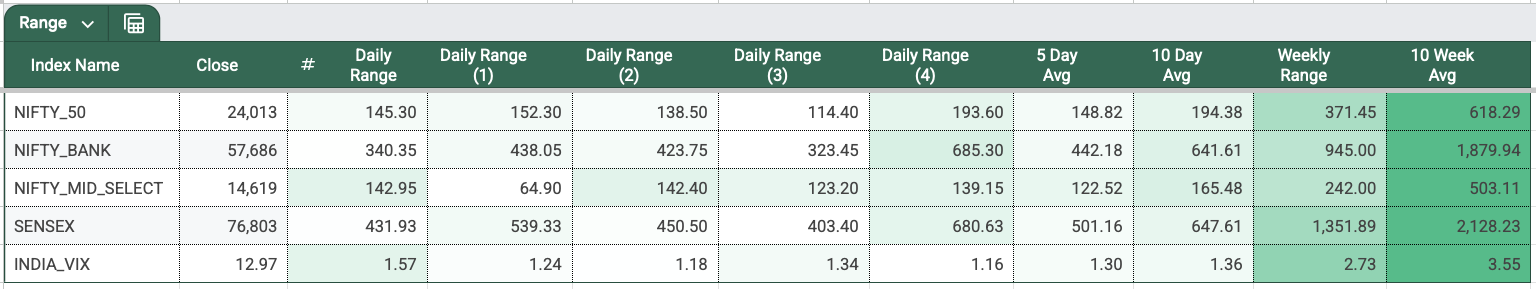
The weekly range came in at just 371 points, down sharply from 575 points last week. India VIX continuing to cool off explains much of this. The contraction is visible across the board — the 5-day average range has dropped to just 149 points from 240 points last week, suggesting that the wild swings of 2026 are finally beginning to settle down. The daily ranges tell the same story: the widest day of the week was just 194 points, while Tuesday was the narrowest at 114 points.
For the first time in a while, the market seems to be pricing in less uncertainty. Whether it’s the easing of geopolitical concerns or simply the absence of a fresh crisis every weekend, lower VIX is now translating into narrower daily ranges.
Daily
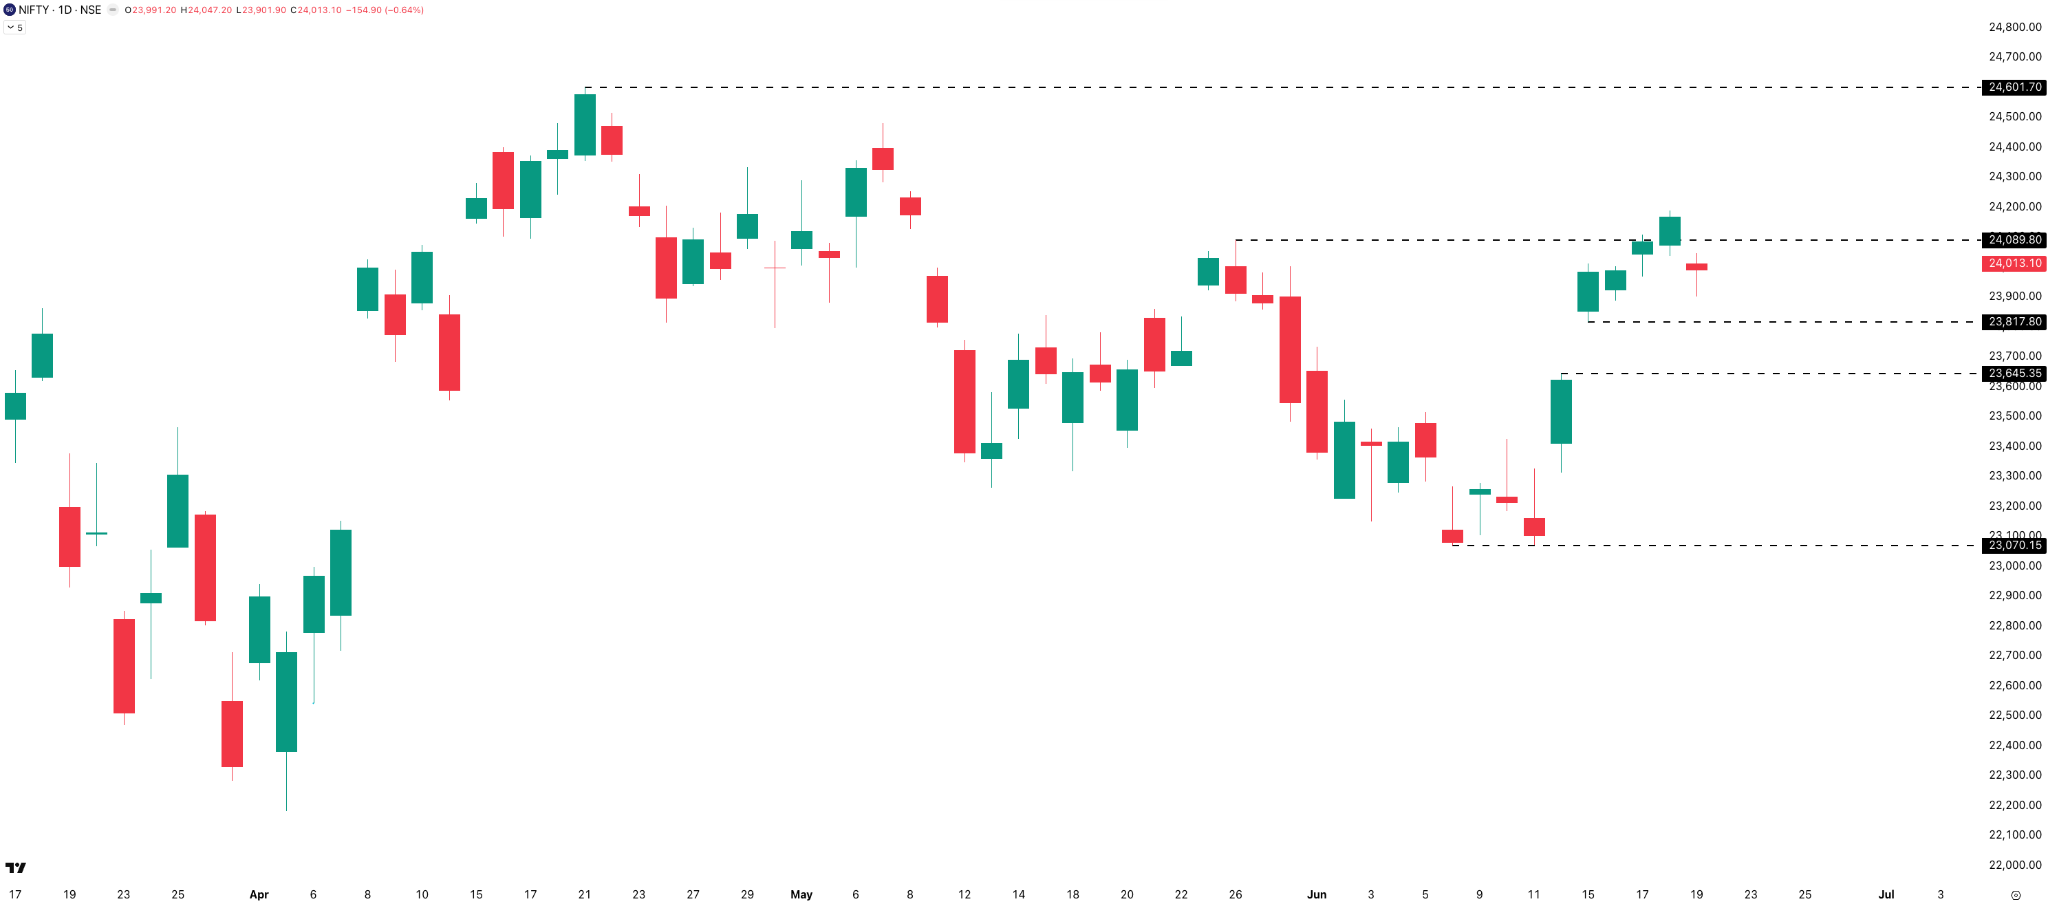
Nifty started the week with a gap-up opening and continued higher for four straight sessions, reclaiming 24,000 and moving above 24,150. Friday saw a gap-down opening and a sell-off through the day, but Nifty still managed to close the week above the important 24,000 mark.
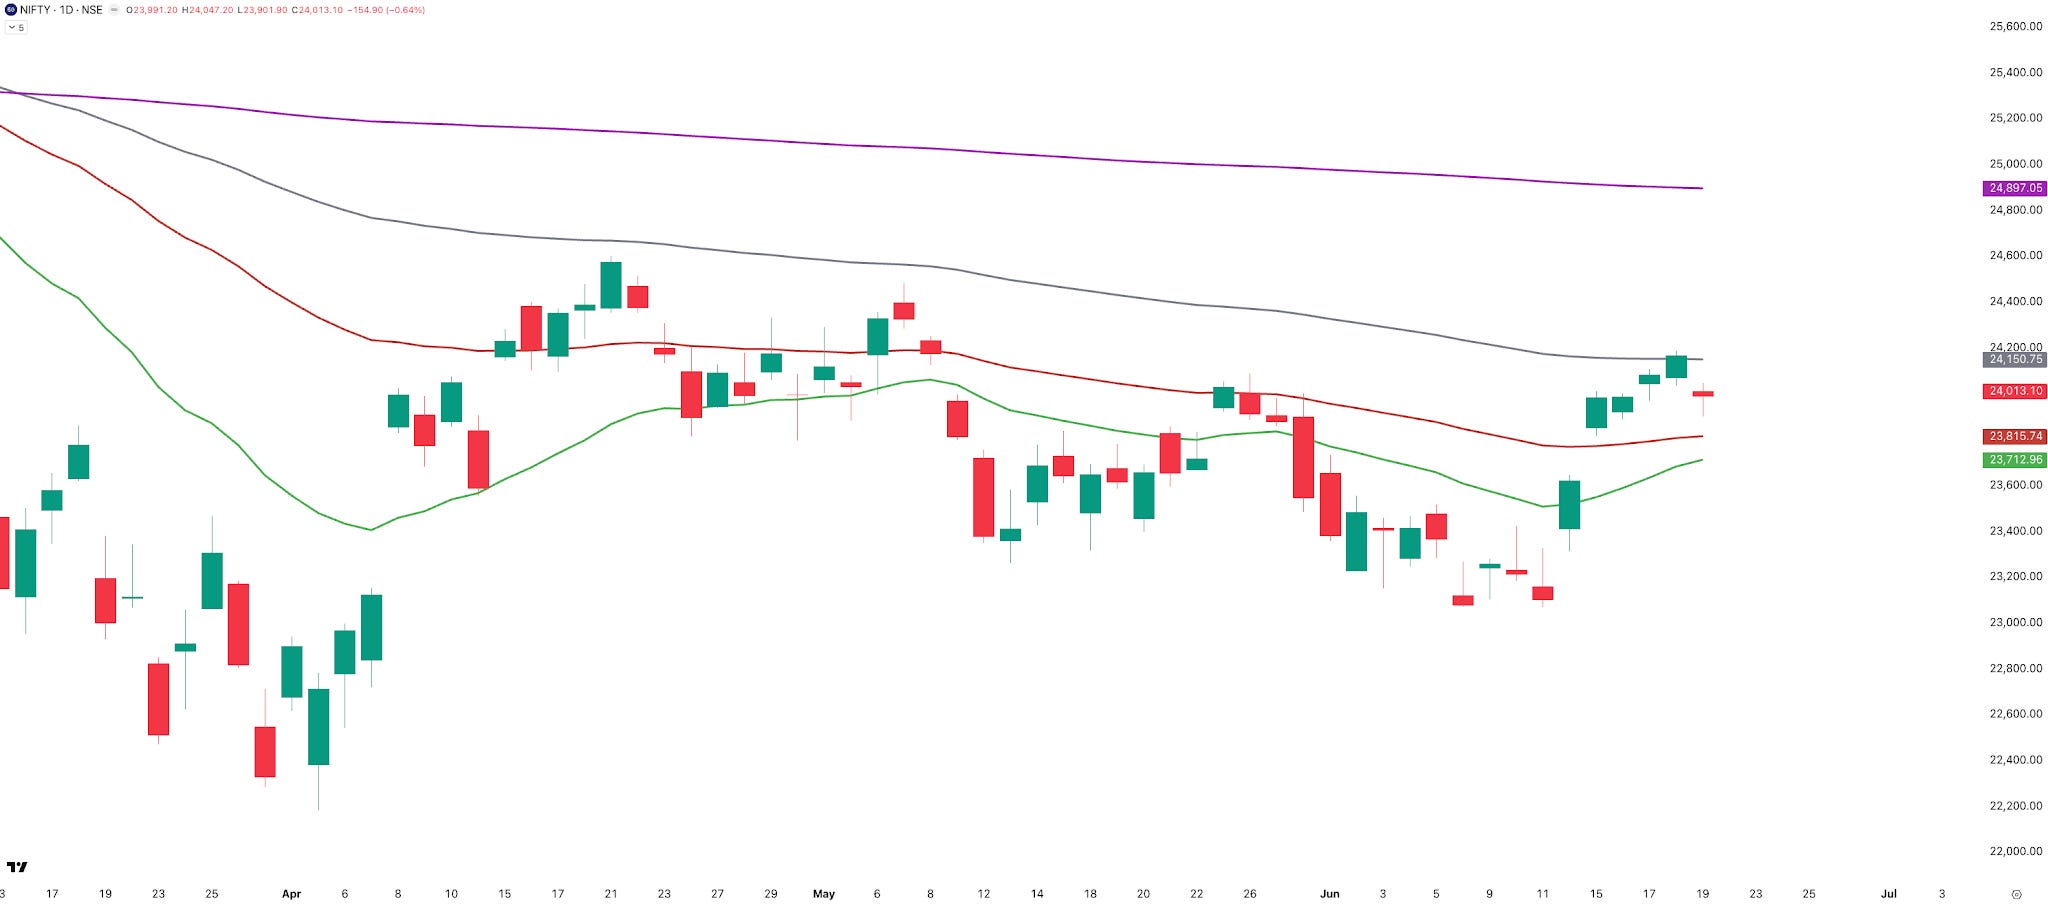
Nifty is now trading above both the 21 EMA and the 50 EMA, and is getting very close to the 100-day EMA. The 200-day SMA at 24,900, however, remains some distance away and continues to be the biggest hurdle overhead. Encouraging signs — but one step at a time.
Hourly
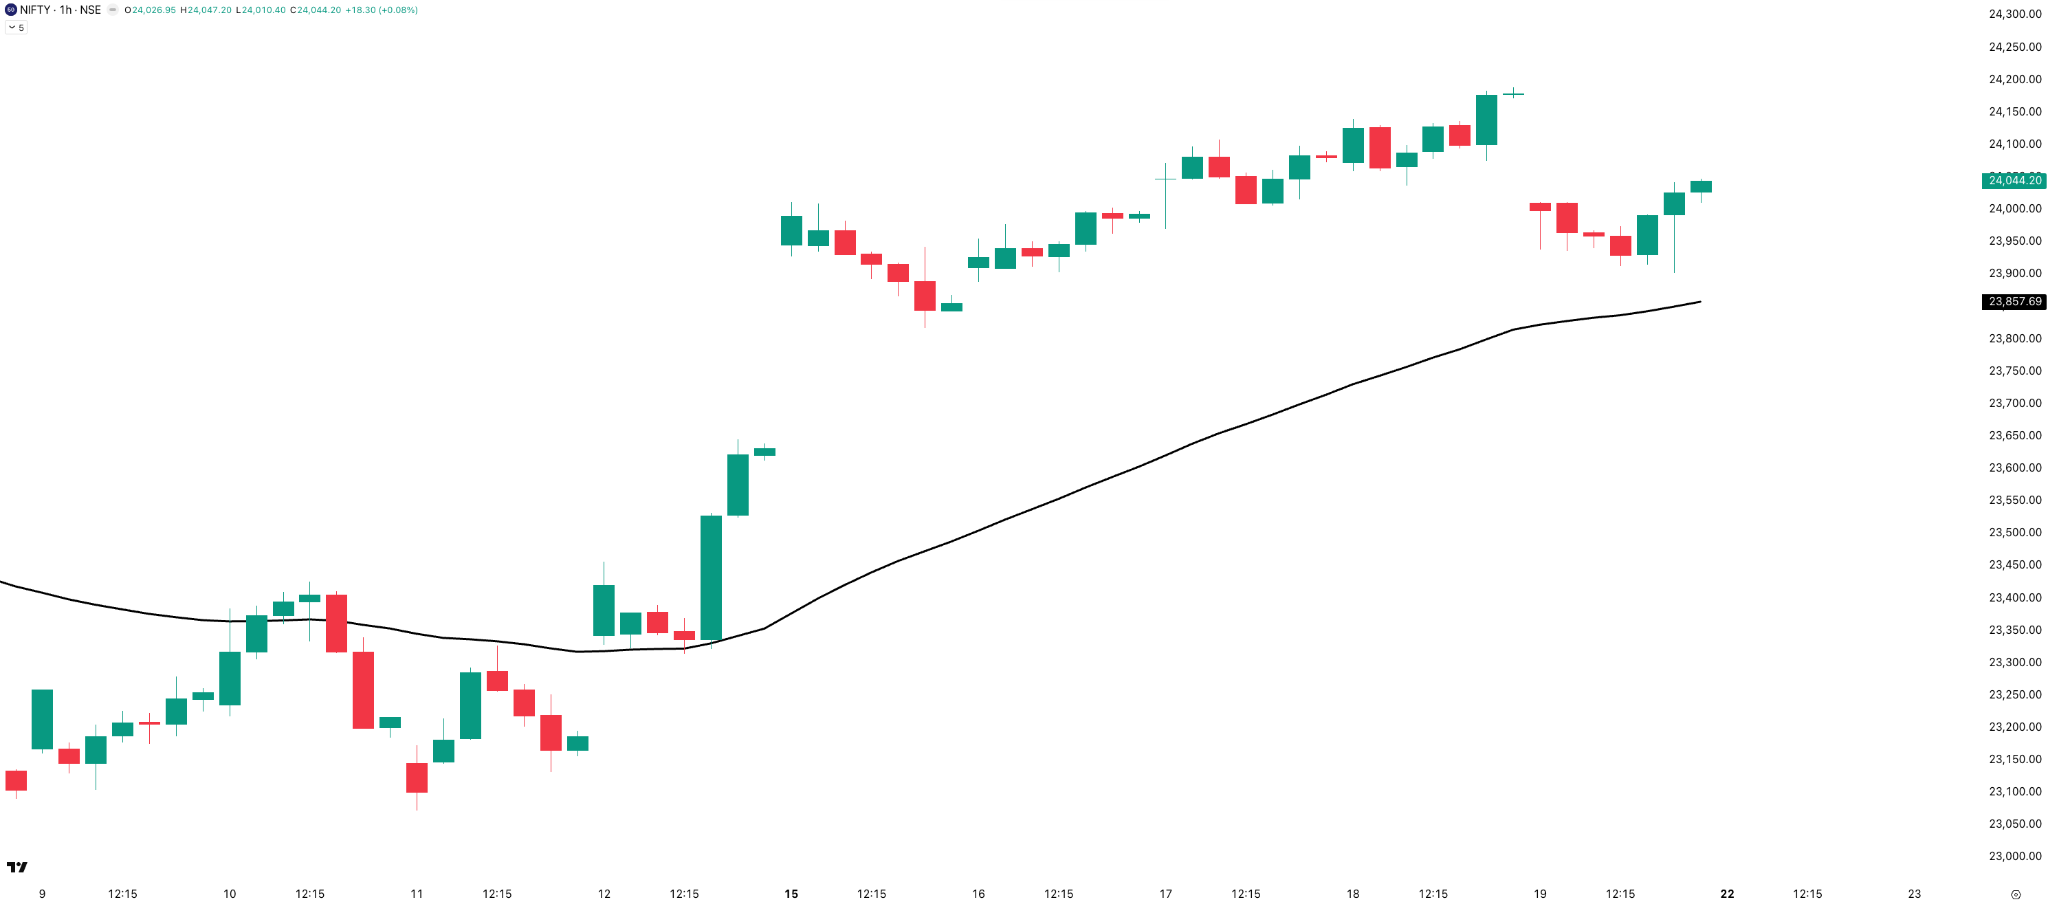
Nifty remained comfortably above the 50 EMA for all of the week. Monday’s gap-up move set the tone, and the index continued making higher highs until Thursday’s close. Friday’s gap-down opening did push price towards the EMA, but it closed above it at the end of the day. For now, the hourly trend continues to remain positive.
Nifty Weekly Expiry — Tuesday, 16 June
One of those rare expiries where realised volatility came in lower than what options were pricing in. The ATM straddle opened at 116 points, while the entire day’s range was just 114 points. That’s about as good as it gets for non-directional options sellers. Despite the low premium, the market stayed within the range implied by the straddle throughout the day. Let me know in the comments how your expiry went.
Section 2 — What to Expect in the Coming Week
NIFTY
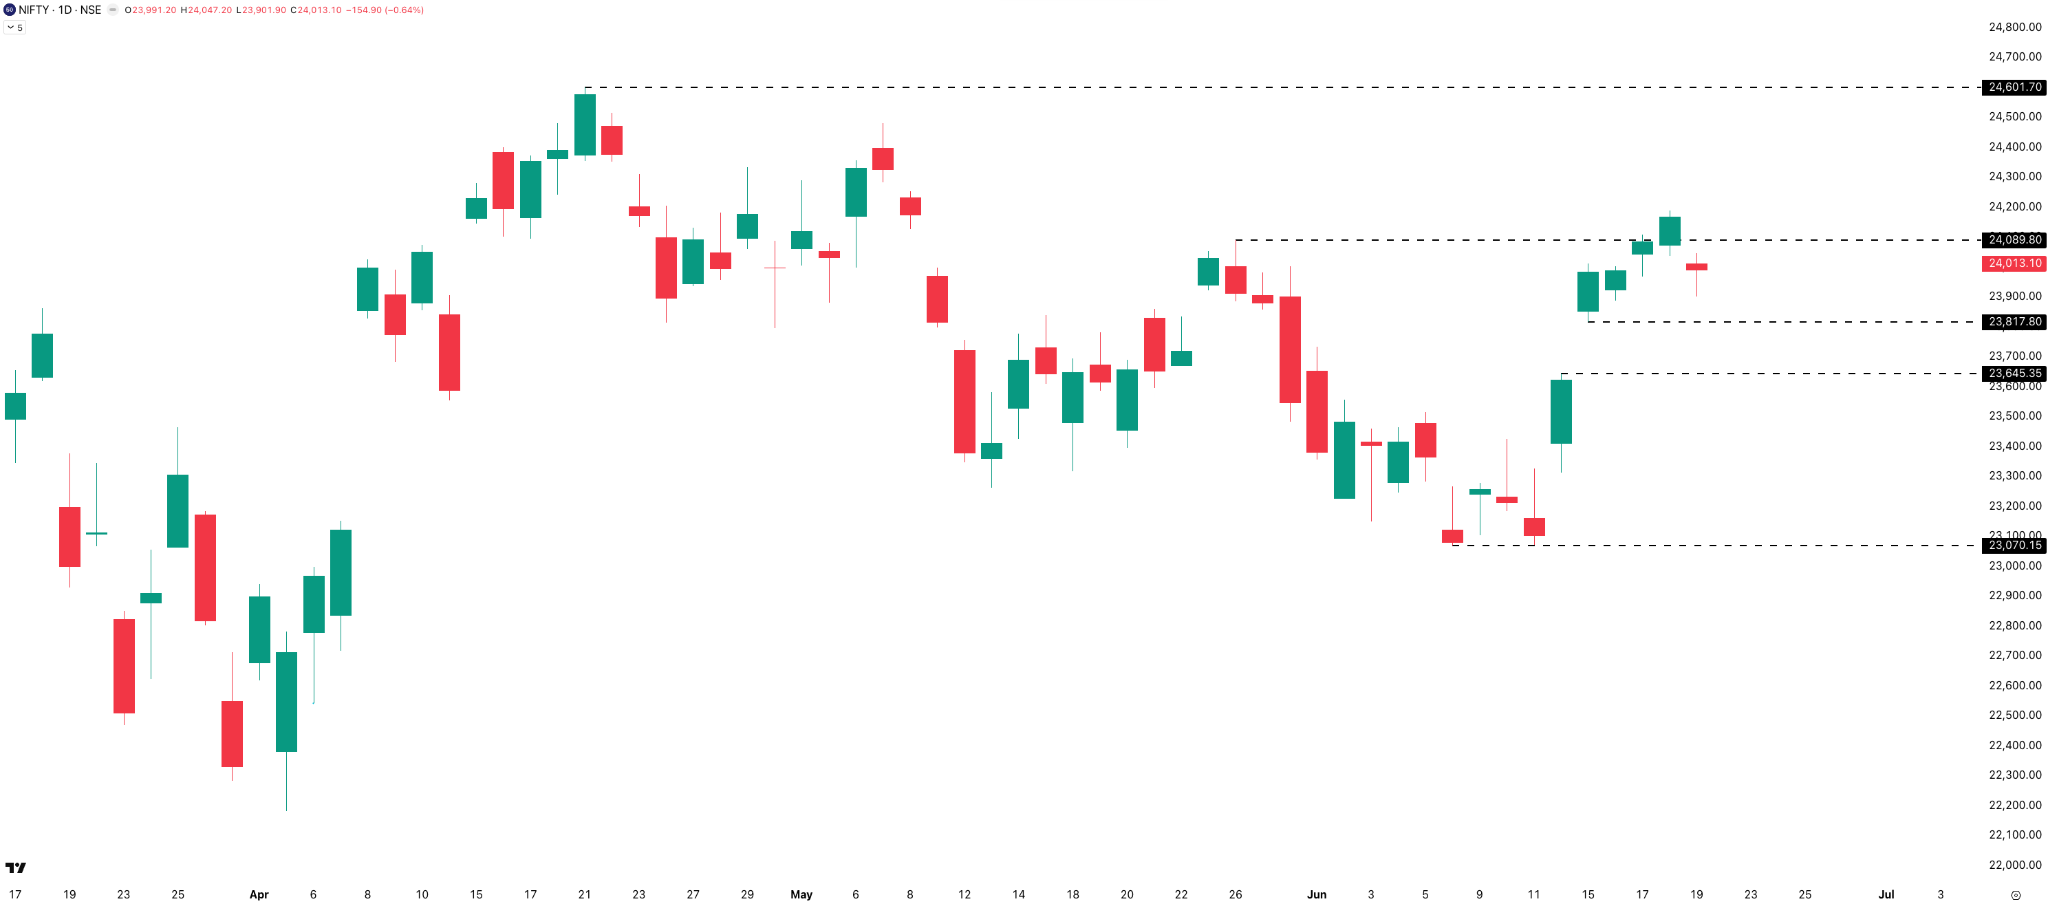
The 24,000 level has now flipped from resistance to support, with Nifty spending most of the week above it. Below that, the 23,800 to 23,650 gap zone is the next area to watch and could act as support if the market pulls back.
On the upside, 24,200 remains the immediate hurdle. A sustained move above that could open the door for a retest of 24,600, which continues to be the key resistance level.
The overall bias remains bullish-sideways .
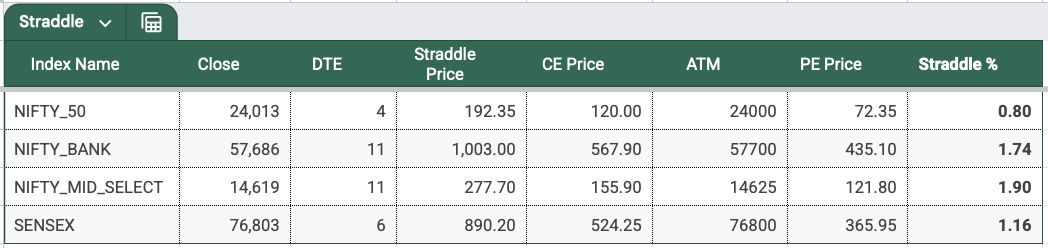
The Nifty ATM straddle closed at 192 points, down sharply from 281 points last week, implying an expected move of roughly 0.8% on either side. That gives an expected range of 24,205 on the upside and 23,821 on the downside for the upcoming weekly expiry on Tuesday, 23 June .
With India VIX now below 13 and daily ranges contracting, the options market is clearly pricing in a much calmer week ahead.
India VIX
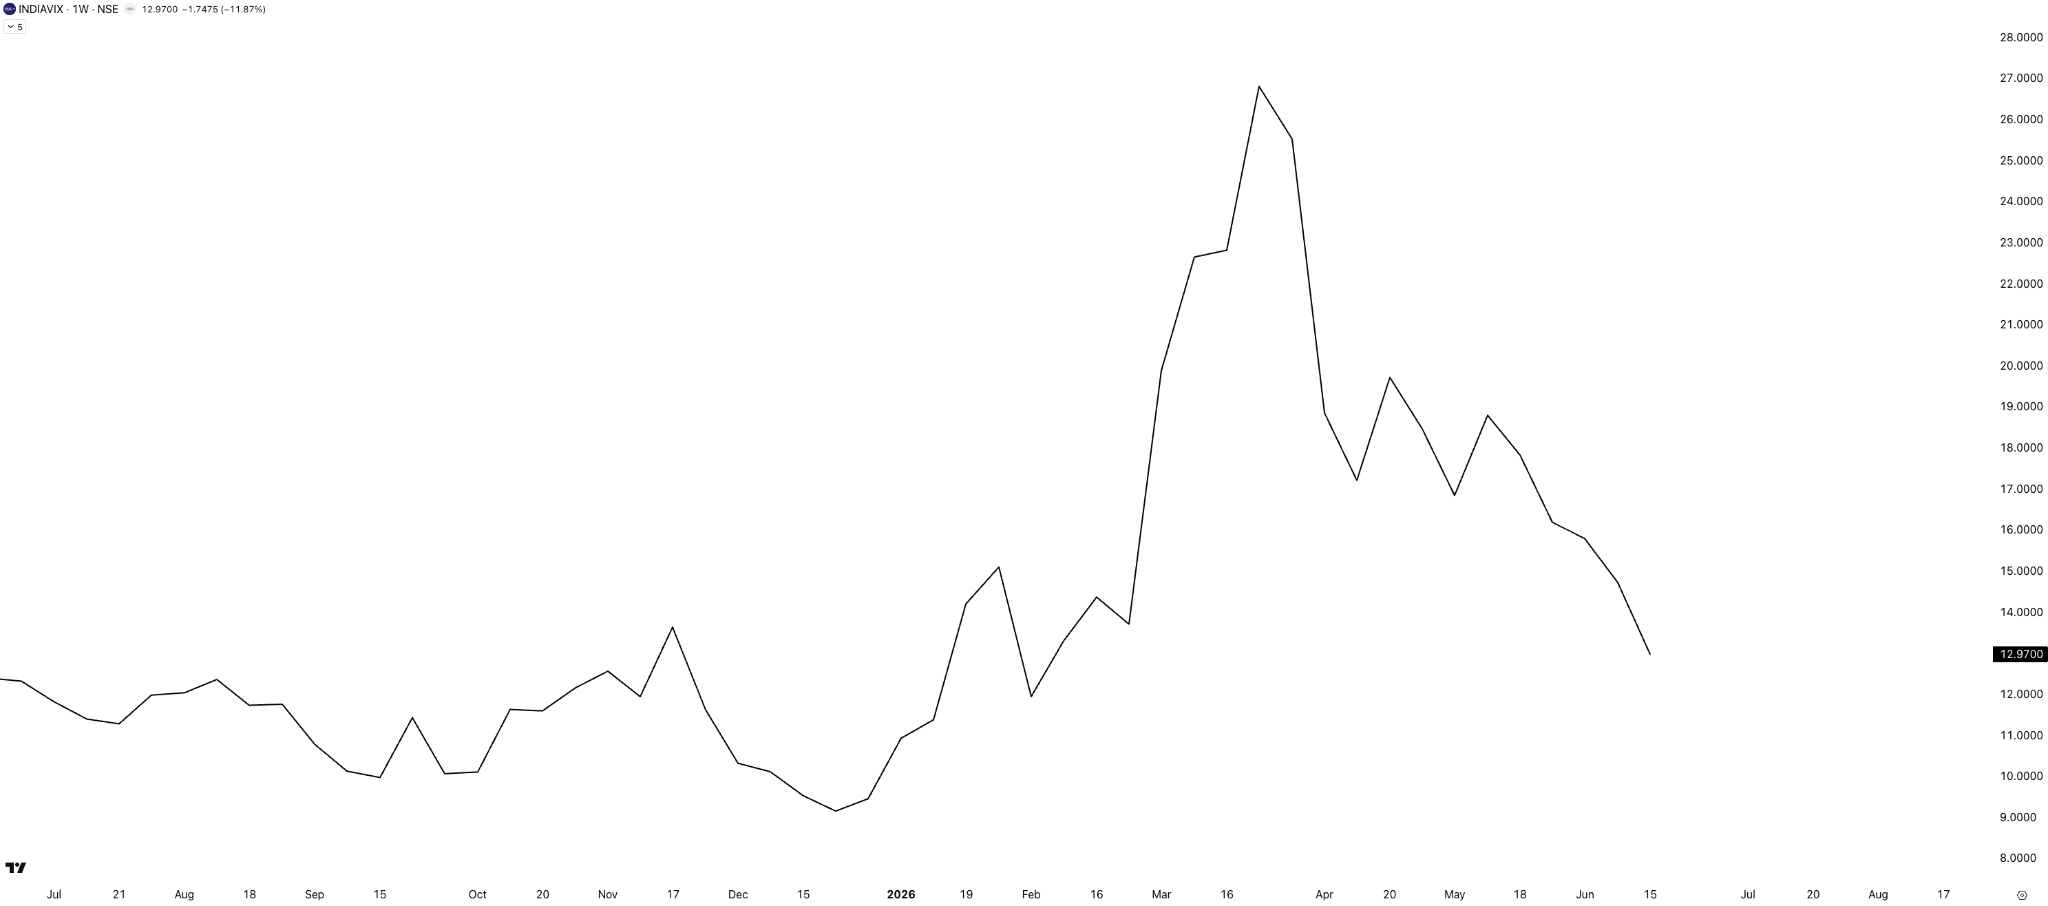
India VIX fell 12% this week, closing below 13 for the first time since the first week of February 2026. Lower VIX is already translating into narrower daily ranges and a more predictable market environment — something traders haven’t had much of in 2026.
Sectoral Performance
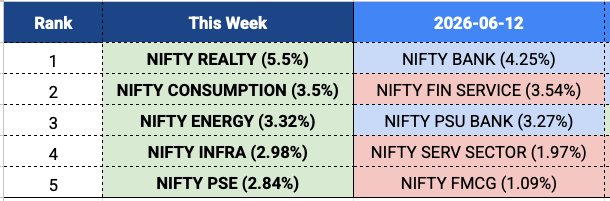
Nifty sector view: After two weeks of financials dominating the leaderboard, we have an entirely different top five this week. Nifty Realty takes the top spot with a 5.5% gain, followed by Consumption at 3.5% and Energy at 3.3%. Infra and PSE round out the top five with gains of 3% and 2.8%, respectively. There isn’t a single financial sector in the top five this week. Leadership has broadened out — generally a healthy sign for the market.
Tijori index view: Communication Equipment again — worth double-clicking on if you haven’t already, given how many times it has appeared in this list. Then Defence, General Insurance, Wires & Cables making a comeback, and Insurance.
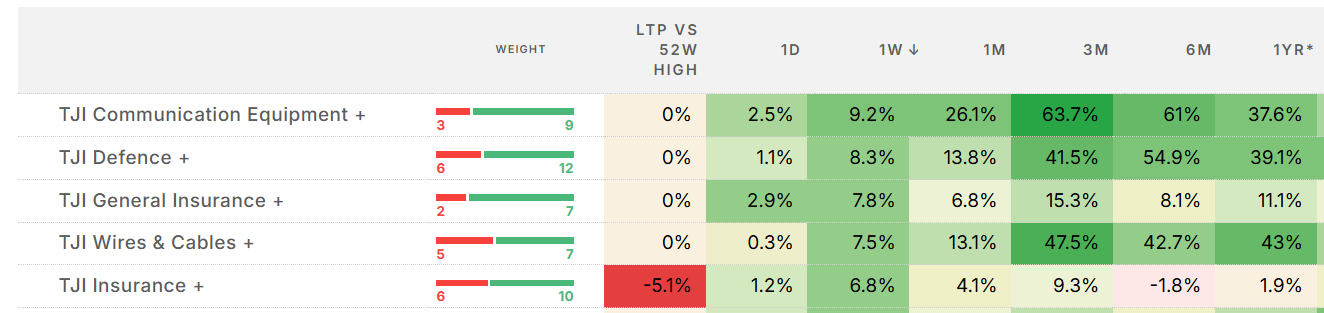
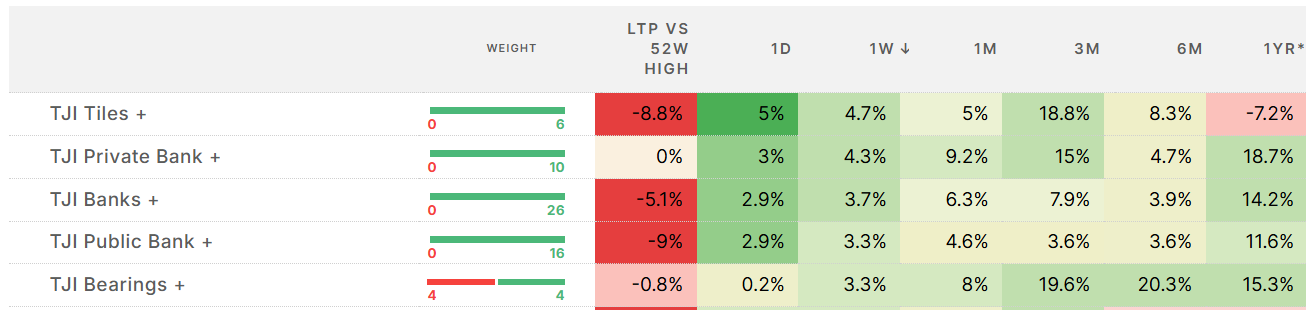
On Insurance — back in the early 1990s, when NSE was being set up, institutions like LIC, GIC Re, and New India Assurance became shareholders at prices that today look almost unbelievable. With NSE filing its IPO papers this week, the market finally has a much clearer benchmark for what those holdings could be worth. GIC Re and New India Assurance are among the shareholders participating in the offer-for-sale, while LIC continues to remain NSE’s largest shareholder. Whether this week’s move in insurance stocks was entirely because of the NSE IPO is difficult to say — but the timing is certainly interesting.
A word on IT: everyone seems to be writing an obituary for Indian IT services. Nifty IT dropped over 6% right after Friday’s opening bell — Infosys, TCS, HCL Tech, all sliding — after Accenture cut its FY27 revenue guidance, citing the West Asia crisis. But the deeper worry predates this week. Vishal Sikka, who once made Infosys an early OpenAI investor, told CNBC this week that IT companies should go private — public markets demand quarterly predictability, and that’s exactly what stops radical reinvention, the kind Netflix made when it killed its own DVD business.
There are also growing murmurs of layoffs across IT product and services companies. The old bull case was that AI would expand demand for IT services. But what’s playing out looks like the opposite.
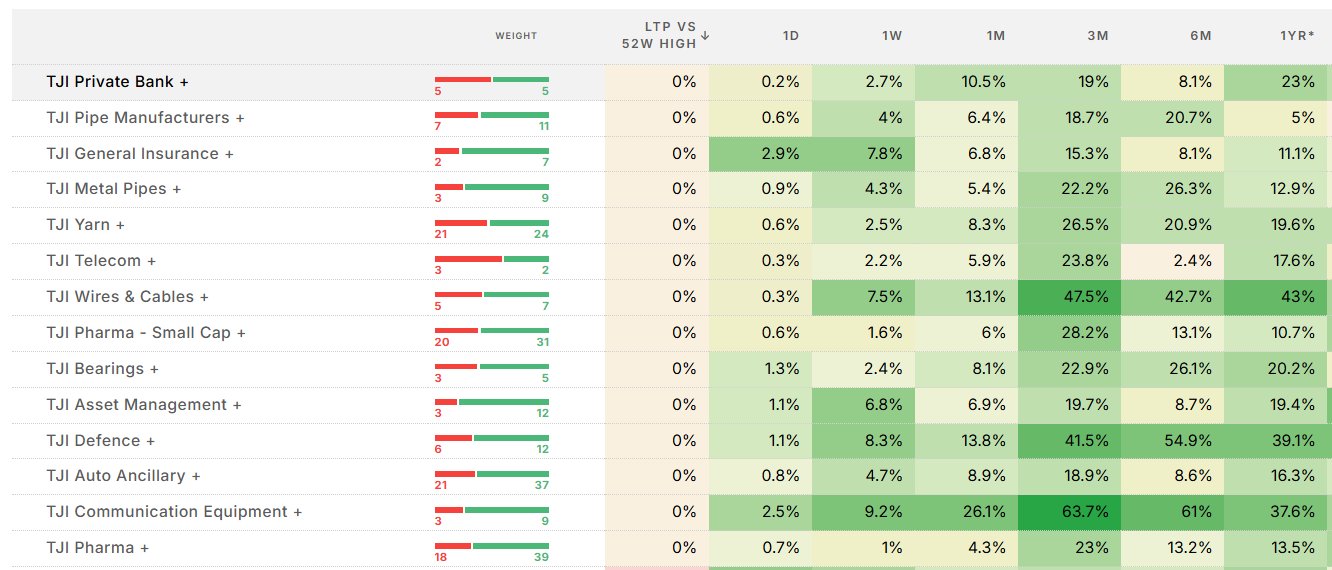
52-week high breadth: 14 Tijori indexes are near their 52-week highs this week — a new high for this metric, and market breadth that hasn’t been seen in a while.
Commodities
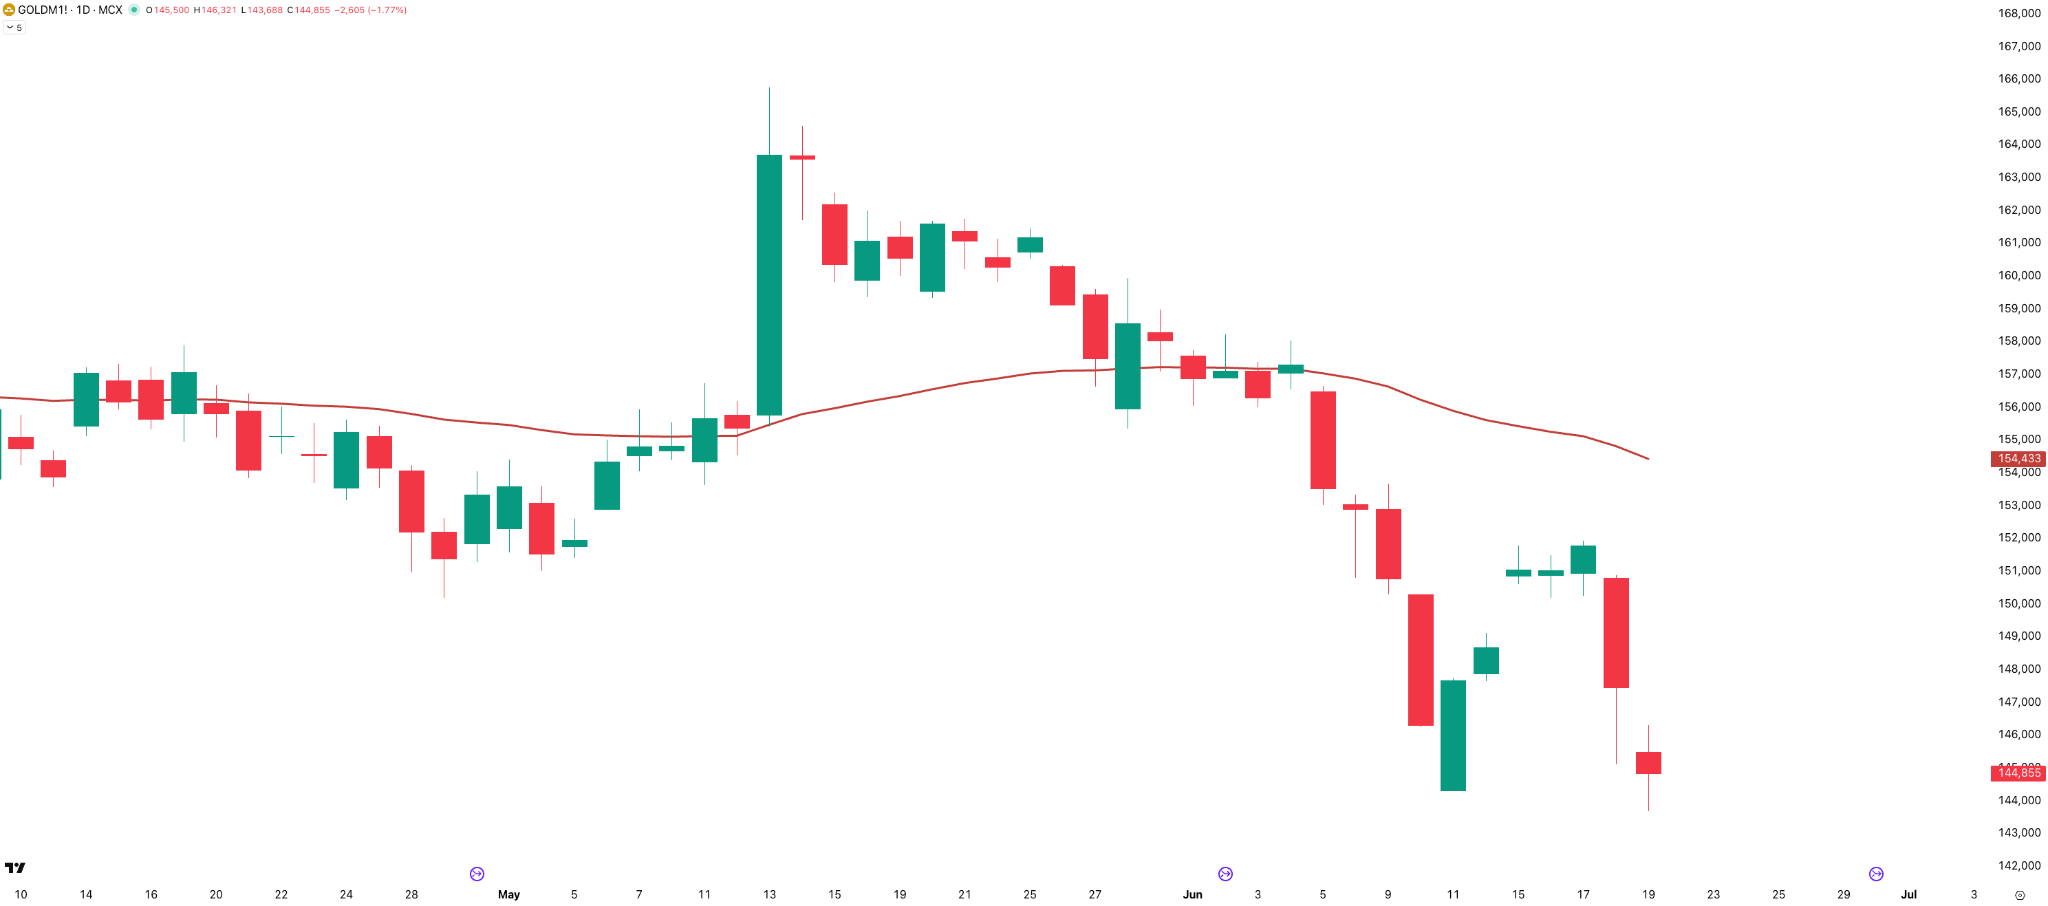
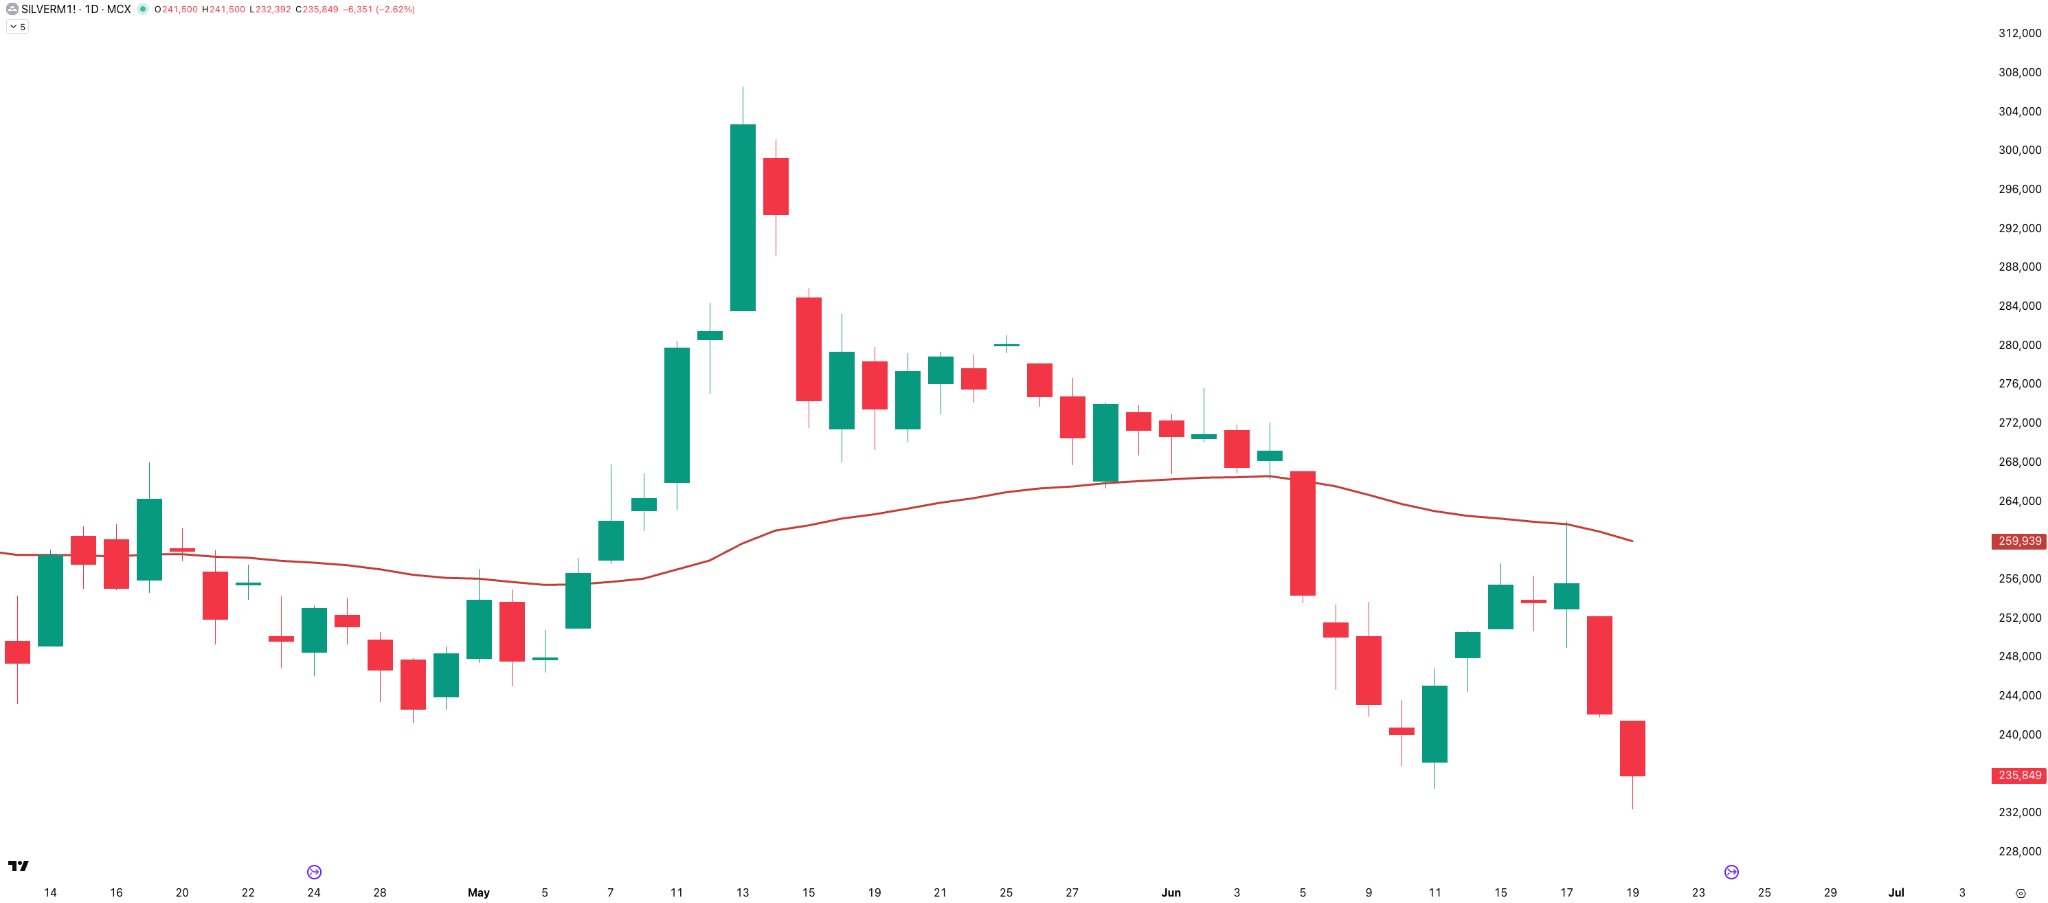
On the daily timeframe, both Gold and Silver continue to look weak. Gold futures are trading around ₹1,44,900, well below the 50 EMA at ₹1,54,400. After a brief bounce last week, sellers stepped back in and pushed prices lower. Silver tells a very similar story — currently trading around ₹2,35,800, significantly below the 50 EMA at ₹2,59,900, and has given up most of last week’s recovery. Both metals remain below their 50 EMAs, and the trend continues to be down.
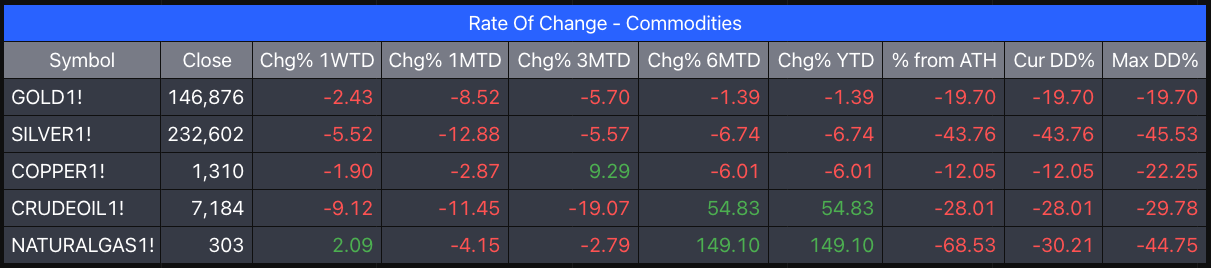
On a weekly basis, it was a red week for most commodities. Crude Oil was the biggest loser, down 9.1%, giving up a large part of its recent gains. Silver fell 5.5%, Gold was down 2.4%, and Copper slipped 1.9%. The only exception was Natural Gas, which gained 2.1% for the week.
Despite the recent weakness, Crude Oil is still up nearly 55% in 2026, while Natural Gas remains the best-performing commodity of the year with gains of 149%.
Summary
Markets ended the third week of June on a strong note, with Nifty gaining 1.65% and reclaiming the 24,000 mark. The Iran deal finally getting signed, and the RBI’s new dollar swap facilities helped cool nerves, with India VIX falling below 13 for the first time since February.
The broader market continues to outperform. Microcap 250 remains the standout performer of 2026, while Nifty 50 is still down over 8% for the year. On the sectoral front, leadership shifted from financials to Realty, Consumption, and Energy. Market breadth also improved significantly, with 14 Tijori indexes now trading near their 52-week highs.
Commodities remained weak, with Crude Oil, Gold, and Silver all ending the week in the red.
The bottom line: Nifty is back above 24,000, volatility is cooling, and the overall bias remains bullish-sideways .
What Caught My Attention This Week
Read: Tim Urban’s blog post — “How and Why SpaceX Will Colonize Mars” on Wait But Why. Ten years old, but still one of the best explanations out there of why we landed on the moon in 1969 and then, strangely, just stopped. Urban walks through the whole history — the Cold War space race, satellites, probes, the ISS — building up to the question of why Musk is betting on Mars. Worth the read to decide whether that trillion-dollar valuation is actually worth it. Read it here
Read: Derek Thompson’s essay — “The Cult of the Enhanced Self.” It’s about Oura rings, GLP-1s, and the growing instinct to run your own body like a startup that needs optimising. Thompson isn’t saying it doesn’t work — by every health metric, it does work. We will have fitter people, far fewer diseases, and longer lives. His worry is what it may be costing us. The more we optimise our bodies, the lonelier and less happy we seem to be getting in the process. Read it here
Events to Factor In
Next week is a 4-day trading week . Thursday, 25 June is the monthly expiry for BSE indices — primarily Sensex — and Friday is a market holiday on account of Moharram. No major known macro events are lined up, which should be welcome news after the last few months of headline-driven volatility.
ITR filing season is underway — don’t miss the Substack post titled “Filing ITR — the bare minimum you should know” by Satya Sontanam of Zerodha Varsity.
And do check out Zerodha’s holiday calendar — all long weekends are marked, making it much easier to plan time away from the markets.
Over 2 crore Indians invest with Zerodha. Open a free demat account in minutes and invest in stocks, mutual funds, ETFs, and bonds at 0 brokerage. No hidden charges, no gimmicks. Plus, get free access to research tools like Tijori, Sensibull, and more.
If you find this series useful, don’t forget to subscribe to the channel — and do share it with your friends.
Until then — stay curious, stay steady, and enjoy your weekend.