Zerodha: Practice What You Preach?

I recently heard on a podcast Bhuvan say that he personally would not put money in a small finance bank FD even for 3% higher returns because safety matters more.

Yet Zerodha offers small finance bank FDs on Coin.

Isn’t that hypocritical?
Personally avoid a product because you don’t consider the extra return worth the risk, but make the same product convenient for retail investors to buy.

If Zerodha truly puts investors first, shouldn’t the risks be highlighted as prominently as the higher interest rates?

2 Likes

That’s his personal opinion. Nothing to do with Z. :face_holding_back_tears:
If I were to invest in FDs, I would personally put up to 5L in multiple SFB FDs so it remains under the insurance umbrella. :open_umbrella:

Z also offers various debt funds, G-Secs, SDLs - the greater the risk the greater the reward. :zap:
It’s up to each user to choose what’s appropriate for them, either with the knowledge they’ve gained from free learning platforms like Varsity’s personal finance module or by consulting with a financial advisor. :scroll:

2 Likes

wrong .

No fear in investing in small bank FDs as long as you know there is no market crash coming :face_with_monocle:

I invested lot of such 9% deposits in 2022-23 coz I knew markets and economy were safest then. Coz lightning doesnt strike twice. Meanwhile bears were daily dreaming about crash that time :joy:

Just your FD duration should be such that expiry date is before the next crash :partying_face:

1 Like
3 Likes

Every bank is safe untill it collapse,so don’t worry too much

3 Likes

No way GoI would let a systemically important bank like SBI go under. :face_holding_back_tears:

That’s what she said when I ask about her ex because I am also systematically important for her financials

2 Likes

Bhuvan here. Emphasis on the “Personal.”

No. It’s not hypocritical. Real hypocrisy would’ve been me hiding my opinion. Also, it’s “personal.” I never said everybody should follow what I say. I also took great pains to emphasize that what I said is “irrational.”

Might I also add there is personal in personal finance?

4 Likes

Fair point Bhuvan. Hypocrisy may have been too strong a word.

But my point was not that your personal choice should become Zerodha’s policy.

My point is simple. If someone with your financial knowledge thinks an extra 3% return is not worth the risk then should the average retail investor not be made equally aware of that risk when Zerodha offers the higher return?

Personal finance is personal but the way a product is presented also influences people’s decisions.

That is what I was questioning.

1 Like

@Bhuvan you are perfectly in the clear if we follow the usual conventions.

But, the apparent contradiction starts to appear
if we start applying the higher standards that Zerodha claims to adhere to.


[ Source ]

While i continue to personally believe folks’ heart is in the right place,
recent updates have often reminded me of the sentiment -
“The road to hell is paved with good intentions.”

Of course, there’s the fine-line between offering vs. pushing.
While Zerodha can continue to claim even today that they are not pushing such stuff,
but, simply offering (even without pushing) appears to be a compromise,
the start of a slippery-slope.

< End of observation. Start of an opinion. >

One aspect that would help improve confidence in Zerodha would be
to promote public activities/interactions within Zerodha that demonstrate
that Zerodha is not operating on the current principles with a bus-factor of 1.

From the outside,
it is absolutely unclear that

  • the mission statement / driving principles
    are distilled into the rest of system / the decision makers
  • the current mission is not being constantly enforced top-down,
    and that it will survive the inevitable bumps down the road in future.

FWIW, some of the claims about the limited hierarchy and limited operational oversight discussed in this video do give confidence that the mission-statement is here to stay. Hopefully, more of this, more prominently, and more in day-to-day interactions (what % of folks outside Zerodha woudl have even seen that video!). How to? That too without “marketing”. Looking forward to seeing this seemingly contradictory puzzle cracked.

@Sagar_Gudekote is this :point_up_2:t3: something that falls under your purview?

1 Like

Until it’s out of the government’s control.

I also said that 5 lakhs is guaranteed. We aren’t telling people to put all their life savings; right? Nothing is hidden or obfuscated. I’ve no clue what the contradiction here is. We aren’t selling a product that’s “bad” or outright “risky.” We mention the guarantee bit on the platform well. That being said, I do what works for me with my personal finances, and I’ve said as much. :slight_smile:

3 Likes

Not worth the risk "for me. " I personally also think it’s a waste of time, again, for me. Should everyone do the same as me? No. To each their own. Also, I don’t understand where the “Zerodha” point or policy is coming from. These deposits are guaranteed till 5 lks so, ultimately, it’s a question of whether you are comfortable with that guarantee or not. Whatever I say is immaterial.

The responsibility to make good choices lies on the investor. You could hold me to a higher standard if I made a false claim or misled or said something illogical or without basis. To the best of my ability, I’ve explained my point of view :slight_smile:

My philosophy with fixed income has always been simple: I think chasing yield is a waste of time for me. I have better things to do in life.

4 Likes

If Zerodha, starts imposing personal beliefs and preferences on their clients, it will be quite draconian.

Else are we all just supposed to invest in Mutual funds and sit quietly ? Or even further, restrict to funds that Bhuvan or someone else personally approves of ?

Some of this will be subjective, but clearly there is a use case of under 5L here
Beyond that, perhaps they could give a warning for banks with low credit ratings.

4 Likes

TL;DR - Zerodha’s mission statement requires a higher standard
of not just avoiding hypocrisy,
but even avoiding the appearance of hypocrisy by any stretch of imagination.

Personally, i cannot see how that can be achieved in today’s world.
But, hoping Zerodha finds out a way to do so.


Since you ask, trying one more time.

The contradiction is having a particular personal view
and offering products that do NOT strictly conform to the view
AND claiming the mission statement that Zerodha does.

@Bhuvan while it is just one person who has voiced their concern
(based on appearances) in this thread,
please consider the thousands who are silently (mis)judging Zerodha.

Right.
So, how to put this front-and-centre
in front of everyone who watches that video
and silently misjudges Zerodha
without giving you an opportunity to clarify their incorrect jump(s) to conclusion(s)?

Please think of approaches to ensure
how to not just stick to the higher standard of quality/trust that Zerodha aspires to
but also appear to do so without any scope for contradictions.
(there’s only so many folks one can keep clarifying one’s actions to)

While Zerodha continues to be focussing on trust as the USP,
and IMHO is still the most trustworthy compared to others,
the (appearance of a) downward trend in trustworthy actions, is unnerving.

I hope to highlight that it is
becoming increasingly difficult to buy-in into
the highest standards Zerodha sets for themselves.

Please see if can make it easier by avoiding even any appearances of conflicts.

@Bhuvan Remember the feeling from the following bit ?

The result is a dangerous new condition.
Highly credentialed people are now speaking entirely out of their ass.
We are facing a crisis never seen before in the history of humanity. Things are bad.

How to ensure that Zerodha doesn’t come across as being infected with this
by any sort of abstract pattern matching that folks sub-consciously do?

PS: While i was sharing the above reference, the irony is not lost on me. :blush:
But, it’s a thought, one that i feel strongly enough to share it here.

PPS: I agree with the personal views on FDs/bonds, that is not the concern. In fact, folks have wondered on this forum how Zerodha can offer MTF and still claim to act in the best interests of the individual (and have received sufficient clarifications that resolve what appear to be a contradiction at first sight). The concern is that a lot of the thoughts/opinions and Zerodha’s actions are easily misunderstood/misconstrued. The obvious/simplest interpretation often being in conflict with Zerodha’s mission statement. Does anyone at Zerodha red-team outgoing public communications to ensure such instances are pro-actively identified/avoided?
No country that issues debt in its own currency would involuntarily default on them - it can always inflate/print its way out of such debts! :money_with_wings:
So worst case - depositors holding INR would be made whole (though whatever that’s worth in a collapse is debatable) but those with dollar deposits (FCNR et al.) would be left holding the bag. :moneybag::arrow_right::luggage:

I don’t understand the criticisms leveled against Z and @Bhuvan in this thread at all! :face_with_spiral_eyes:
He’s repeatedly made his position clear in both the video and here, that the FD thing is his personal opinion and has to do with his personal finances. :bearded_person::bank:

Z’s stated goal is to make all RBI/SEBI approved investing vehicles available for its users without pushing anyone into any product, all at discount brokerage rates. They spend quite a lot to educate users, but if the users refuse to learn… :person_shrugging:

As @SpacemanSpiff has already said - on principle, Z or any broker shouldn’t decide which products its users get to trade/invest. :white_check_mark:

5 Likes

Consider wars and forced takeovers. Things like Gold is gold no matter who rules.

Hmmm… OK.

A TL;DR of my above TL;DR -

The recent growing perception of contradiction
between Zerodha’s stated mission and actions,
a. Has Zerodha noticed it?
b. If yes, does Zerodha consider it an issue?
c. if yes, what are the plans to address it / reverse the trend?


@pavinjoseph, as an active member on this forum in recent times,
i hope you remember the posts on this forum that point out
what folks perceive to be contradictions in Zerodha’s stated goal/mission and their offerings.
(sure sure, a couple of posts doesn’t make a trend)

In one of his recent personal thoughts.
@nithin recently shared and introspected on this sentiment of
“To run a brokerage firm is to live with contradictions”,

i wonder how long it will take
for the sentiment to spread through the rest of Zerodha
(or maybe if it has already),
and what Zerodha intends to do about minimizing the seeming/perceived contradictions ?


Again, i have no criticism specifically against the logic Bhuvan expressed in the video.
In fact, i have publicly maintained the same attitude towards high-risk debt assets.

While Bhuvan is humble enough to label his well-thought out opinions as possibly irrational,
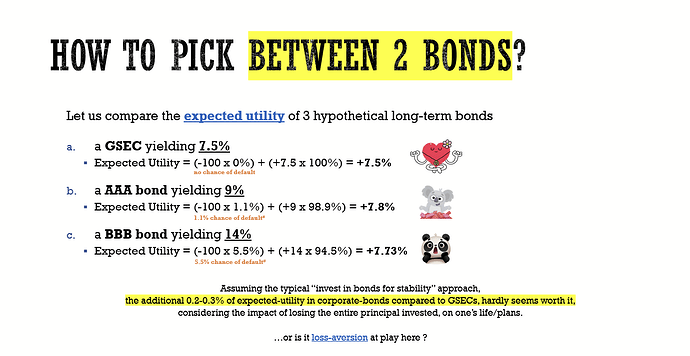
i have gone out on a limb and shared why it makes mathematical sense
image
Note: Strictly speaking, the mathematical calculations above are for “expected-value”.

…and called out chasing higher yields from overtly riskier debt
as being the irrational behavior that folks pursue.

FWIW, high risk debt happens to be the “gateway drug”
that features prominently in my “origin story”. :sweat_smile:

1 Like

That’s the risk of the online world. A misunderstanding can travel around the world before a clarification ties its shoes. We are honest and transparent in whatever we do, and beyond a point, once you say something or write something, you aren’t in charge of how things are perceived. That’s life, at the risk of sounding flippant.

3 Likes